|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
November 9th 2026 |
|
| NEW |
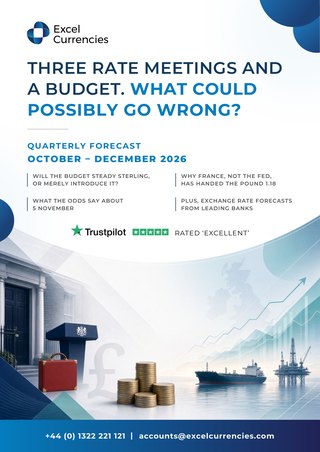
Quarterly Forecast · Q4 2026 |
|
|
| Three rate meetings and a Budget. What could possibly go wrong? |
| October – December 2026 |
| ✓ |
Will the Budget steady sterling, or merely introduce it? |
| ✓ |
Why France, not the Fed, handed the pound 1.18 |
| ✓ |
What the odds say about 5 November |
| ✓ |
Exchange rate forecasts from leading banks |
|
|
|
| Where banks see rates by January 2027 |
GBP/EUR
1.12 – 1.19
€70,000 gap on £1m
|
|
GBP/USD
1.28 – 1.35
$70,000 gap on £1m
|
|
EUR/USD
1.13 – 1.16
$30,000 gap on €1m
|
|
| Four dates that could move your rate |
28 OCT
UK Budget
|
28 OCT
Federal Reserve decision
|
29 OCT
ECB decision
|
5 NOV
Bank of England decision
|
|
|
|
| Free PDF · 11 pages · Bank forecasts, key-event calendar & economic outlook |
| Ranges are the spread of published bank and consensus forecasts, Bloomberg, 5 October 2026. Not dealing rates and not an Excel Currencies forecast. |
|
|
| Sterling and Euro Recover Ground Ahead of US CPI and UK GDP |
Today's Key Points
- Sterling and the euro both firmed against the dollar over the past 24 hours as the greenback gave back some of Friday’s post-payrolls gains.
- The US jobs report (165,000 new positions) had briefly strengthened the dollar; Monday’s price action largely reversed that impulse.
- GBP/EUR stayed relatively steady, reflecting similar directional moves in both currencies against the dollar.
- Bank of England Governor Andrew Bailey speaks at 17:25 today; markets will listen for any fresh colour on further rate moves after last week’s hike.
- Attention then shifts to US CPI on Tuesday and the UK’s preliminary GDP figures on Thursday.
- The rest of the week is dominated by inflation and growth data rather than central-bank decisions.
- Overall tone is one of measured digestion after last week’s BoE hike and strong US labour data, with no fresh UK political shocks moving the market in the last day.
- Even a quiet cross still moves the numbers: see the table showing the euro difference on a £250,000 transfer – up to €9,975 between the three-month low and the recent high.
- With US CPI tomorrow and UK GDP on Thursday, know where the banks see sterling heading: download our free Q4 Quarterly Forecast for rate forecasts, the key-event calendar and what this week’s data could mean for your transfer.
Market Overview
The past 24 hours have been characterised by a gentle unwind of Friday’s dollar strength. Stronger-than-expected US non-farm payrolls (165,000) had lifted the greenback late last week; by Monday the dollar was softer across the board, allowing both sterling and the euro to reclaim ground. GBP/USD recovered roughly half a percent while EUR/USD added a similar amount, leaving the cross relatively quiet. Last week’s Bank of England rate increase to 4% (the first rise in three years) remains the dominant UK narrative, with markets still weighing the possibility of a further move if energy prices stay elevated.
No material UK political developments altered pricing in the last day; the recent Budget appears to have been absorbed without lasting currency impact. Looking ahead, the week is book-ended by US CPI on Tuesday and UK GDP on Thursday. These releases will test whether the current relative calm holds or whether the data forces a reappraisal of the rate path on either side of the Atlantic. In such an environment the precise moment a transfer is instructed, and the smoothness with which it is executed, can matter as much as the mid-market rate itself – particularly when liquidity thins around high-impact data.
GBP/EUR Analysis
GBP/EUR: consolidating near recent highs; cross relatively quiet
Sterling has traded in a narrow band against the euro since the weekend, consolidating near recent highs after the BoE’s hike last Thursday. The pair’s relative stability reflects the fact that both currencies have moved in the same direction against the dollar, limiting cross-rate volatility.
- Dollar softness on Monday supported both GBP and EUR, leaving the cross almost unchanged on the day.
- Markets continue to digest Bailey’s post-hike comments that further tightening is possible if energy-related inflation risks persist.
- No fresh domestic political or data surprises disturbed the pair in the past 24 hours.
- Focus now turns to Bailey’s speech later today and to Thursday’s UK GDP release for any shift in relative growth expectations.
Educational note: When two currencies share a common external driver (in this case the dollar), the cross can appear deceptively quiet even while each leg is moving. That quiet can mask the value of precise timing: a transfer executed just before a data-driven swing in either leg can still capture or forfeit a meaningful sum once the full process – from instruction to settlement – is considered. Over the coming days the interaction between US inflation and UK growth figures will determine whether this relative calm continues or gives way to more pronounced cross moves.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.2016 |
1.1954 |
€300,400 |
€298,850 |
€1,550 |
| 1 Month |
1.2019 |
1.1810 |
€300,475 |
€295,250 |
€5,225 |
| 3 Months |
1.2019 |
1.1620 |
€300,475 |
€290,500 |
€9,975 |
The numbers show movement is real even when the market feels quiet. Most buyers focus on the rate, yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate with poor support or delays can cost more than a well-timed transfer executed smoothly.
For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so the money arrives exactly when needed, without stress?”
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: recovering from Friday’s post-payrolls dip
Cable has recovered from Friday’s post-payrolls dip, trading higher as the dollar softened on Monday. The move largely reversed the greenback’s late-week gains without erasing the broader context of last week’s BoE rate rise.
- Strong US jobs data on Friday initially pushed GBP/USD lower; Monday’s price action has clawed back most of that ground.
- Markets still price the possibility of a further BoE hike if inflation pressures linked to energy prices remain elevated.
- Bailey’s speech this afternoon is the immediate domestic catalyst; any fresh guidance on the pace of further tightening will be watched closely.
- Broader risk sentiment and US yields continue to set the tone for the dollar side of the pair.
Educational note: A half-percent recovery looks modest on a chart, yet on a sizeable transfer it equates to a tangible difference in the amount of dollars received. The practical lesson is that the window between a data release and the moment instructions are placed can be as important as the rate itself. With US CPI due tomorrow, the same dynamic is likely to reappear: the headline number will move the market, but the smoothness and timing of the subsequent transfer will determine how much of that move is captured or missed.
EUR/USD Analysis
EUR/USD: climbing back toward the 1.12 area
The euro has likewise benefited from the dollar’s Monday retreat, climbing back toward the 1.12 area after testing lower levels late last week. The move has been orderly rather than dramatic.
- Friday’s strong US payrolls had weighed on the pair; Monday’s unwind of that dollar strength has restored much of the ground.
- Eurozone-specific news has been limited; attention remains on the external dollar driver and on French fiscal developments that have occasionally weighed on the single currency.
- Divergence versus sterling is modest at present, reflecting similar reactions to the dollar.
- The week ahead brings US CPI on Tuesday, which will be the dominant near-term influence on the pair.
Educational note: When the euro and sterling move in parallel against the dollar, the EUR/USD rate can appear secondary to those holding both currencies. Yet any subsequent divergence – driven, for example, by differing growth or inflation prints – can open a gap that matters for multi-currency transfers. Timing the conversion between the two, or from either into dollars, therefore hinges not only on the absolute rate but on the reliability of the process once the decision is made. Thursday’s UK GDP and Tuesday’s US inflation figures will be the next tests of whether that parallel movement continues.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Mon 9 Nov (Today) |
17:25 |
GBP |
BoE Governor Bailey Speech |
– |
– |
★★★ |
| Tue 10 Nov |
13:30 |
USD |
CPI m/m (Oct) |
– / 0.3% |
0.6% |
★★★ |
| Tue 10 Nov |
13:30 |
USD |
Core CPI m/m (Oct) |
– / 0.2% |
0.3% |
★★★ |
| Thu 12 Nov |
07:00 |
GBP |
GDP Growth Rate QoQ Prel (Q3) |
– / 0.7% |
0.5% |
★★★ |
| Thu 12 Nov |
07:00 |
GBP |
GDP Growth Rate YoY Prel (Q3) |
– / 1.9% |
1.4% |
★★★ |
| Thu 12 Nov |
07:00 |
GBP |
Manufacturing Production m/m (Sep) |
– / –0.5% |
1.2% |
★★ |
| Thu 12 Nov |
07:00 |
GBP |
Goods Trade Balance (Sep) |
– |
– |
★★ |
Events from the past 24 hours are reflected in the pair analyses above.
Conclusion
The market has spent the last day quietly reversing Friday’s dollar gains while digesting last week’s BoE rate rise. With Bailey speaking later today and the main data points still ahead, the tone is one of watchful consolidation rather than conviction. For anyone moving money across these pairs, the practical difference often lies less in the mid-market rate alone and more in the precision of timing and the reliability of execution once the decision is made. The week’s inflation and growth releases will supply the next tests of that balance.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin