|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
November 5th 2026 |
|
| NEW |
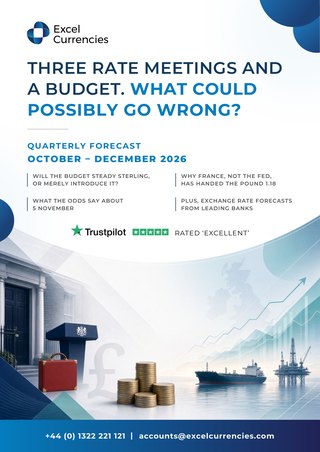
Quarterly Forecast · Q4 2026 |
|
|
| Three rate meetings and a Budget. What could possibly go wrong? |
| October – December 2026 |
| ✓ |
Will the Budget steady sterling, or merely introduce it? |
| ✓ |
Why France, not the Fed, handed the pound 1.18 |
| ✓ |
What the odds say about 5 November |
| ✓ |
Exchange rate forecasts from leading banks |
|
|
|
| Where banks see rates by January 2027 |
GBP/EUR
1.12 – 1.19
€70,000 gap on £1m
|
|
GBP/USD
1.28 – 1.35
$70,000 gap on £1m
|
|
EUR/USD
1.13 – 1.16
$30,000 gap on €1m
|
|
| Four dates that could move your rate |
28 OCT
UK Budget
|
28 OCT
Federal Reserve decision
|
29 OCT
ECB decision
|
5 NOV
Bank of England decision
|
|
|
|
| Free PDF · 11 pages · Bank forecasts, key-event calendar & economic outlook |
| Ranges are the spread of published bank and consensus forecasts, Bloomberg, 5 October 2026. Not dealing rates and not an Excel Currencies forecast. |
|
|
| BoE lifts rates to 4% as inflation path points higher |
Today's Key Points
- The Bank of England raised Bank Rate by 0.25 percentage points to 4% today, the first increase since 2023, with an 8–1 vote; Catherine Mann preferred a larger 0.5-point move.
- Governor Andrew Bailey said the rise was warranted by pipeline inflation pressures from elevated energy prices linked to the Middle East conflict, while cautioning it should not be read as the start of a long automatic sequence of further hikes.
- Markets had largely priced the move; sterling’s reaction was contained, with attention shifting to the updated forecasts (inflation seen near 5% by mid-2027) and the tone of the Monetary Policy Report and press conference.
- The US midterm results (Democratic control of both chambers) earlier in the week continued to support risk sentiment and a softer dollar, aided by lower oil prices.
- Euro-area flash inflation and UK PMI readings earlier in the week provided a steady backdrop without major surprises.
- Looking ahead, Friday’s US non-farm payrolls (October) is the standout release, with euro-area retail sales also due; next week brings US CPI and UK Q3 GDP.
- Overall mood has been orderly rather than dramatic: priced-in central-bank action met with measured responses once the details landed.
- The range still matters after a priced-in hike: see the table showing the euro difference on a £250,000 transfer – up to €10,150 between the three-month low and the recent high.
- With US payrolls tomorrow and UK GDP next week, know where the banks see sterling heading: download our free Q4 Quarterly Forecast for rate forecasts, the key-event calendar and what today’s BoE hike could mean for your transfer.
Market Overview
The past 24 hours have been dominated by the Bank of England’s rate decision at noon UK time and the subsequent commentary. The 25-basis-point rise to 4%, delivered by an 8–1 majority, aligned with consensus expectations following earlier UK inflation readings of 3.5%. Bailey’s remarks emphasised that energy-related pressures justified action now, yet the path ahead remains data-dependent rather than pre-committed. Sterling pairs moved within recent ranges rather than staging a decisive break, illustrating how the detail of the vote, the inflation projection (around 5% by mid-2027) and the press-conference tone mattered at least as much as the headline rate itself.
US midterm outcomes earlier in the week (Democratic majorities in both houses) had already contributed to a softer dollar and firmer risk appetite, reinforced by a sharp drop in oil prices. Euro-area flash CPI and various PMI figures mid-week added colour without altering the broader picture. UK political developments remained secondary to the monetary-policy news. Through the remainder of the week the calendar is front-loaded: Friday’s US employment report will test dollar sentiment, after which attention begins to shift towards next week’s US inflation and UK growth figures. In practice, the difference between a cleanly timed transfer and one that encounters delay or incomplete paperwork can outweigh a few pips of rate movement – especially when settlement windows are tight.
GBP/EUR Analysis
GBP/EUR: consolidating near recent highs after the BoE decision
Sterling–euro has spent the last 24–48 hours consolidating near recent highs after the BoE announcement. The pair absorbed the fully priced 25-basis-point hike without a sharp directional move, as traders focused on the inflation forecast revision and the relatively united but not unanimous vote.
- Key driver: the BoE rate rise to 4% and the accompanying projection that inflation could reach about 5% by mid-2027 on energy effects.
- Secondary influence: earlier UK construction PMI and euro-area producer-price data, both secondary to the policy decision.
- Dollar softness from the midterm results provided an indirect lift via cross-market flows.
Educational note: Rate differentials and inflation projections influence relative currency strength, yet the practical impact on a transfer also depends on the exact moment funds are instructed and the reliability of the subsequent operational steps. With US payrolls tomorrow and UK growth data next week, short-term ranges can widen briefly around releases; a process that is already prepared and clearly communicated tends to absorb those windows more smoothly than one assembled at the last moment.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.2016 |
1.1945 |
€300,400 |
€298,625 |
€1,775 |
| 1 Month |
1.2016 |
1.1785 |
€300,400 |
€294,625 |
€5,775 |
| 3 Months |
1.2016 |
1.1610 |
€300,400 |
€290,250 |
€10,150 |
The numbers show movement is real even when the market feels quiet. Most buyers focus on the rate, yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate with poor support or delays can cost more than a well-timed transfer executed smoothly.
For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so the money arrives exactly when needed, without stress?”
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: tight band, easing modestly after the BoE
Cable has traded in a relatively tight band over the past day, easing modestly after the BoE decision as the hike was already discounted and attention turned to the growth and inflation outlook. The softer dollar backdrop established after the midterms has limited downside.
- Primary driver: BoE communication and the 8–1 vote, which confirmed the rise without signalling an aggressive series of further moves.
- Supporting factor: post-midterm risk appetite and lower oil prices that have weighed on the dollar.
- US jobless claims later in the session provided a secondary data point ahead of Friday’s payrolls.
Educational note: Interest-rate decisions often move a currency less than the subsequent guidance on the path of policy. With payrolls due tomorrow, the dollar side of the pair remains sensitive to labour-market surprises; preparing transfer instructions in advance of the release, rather than reacting in the immediate aftermath, tends to reduce operational friction even if the rate itself is similar.
EUR/USD Analysis
EUR/USD: steady within its recent range
The euro–dollar pair has held steady within its recent range, supported by a softer dollar after the midterms and relatively uneventful euro-area inflation figures earlier in the week. Divergence between the BoE’s hike and the ECB’s more patient stance has been noted but has not produced a sharp cross-driven move.
- Key influence: dollar weakness linked to the midterm outcomes and oil-price declines.
- Euro-specific: flash CPI near expectations and producer-price data that did not alter the broader policy picture.
- Friday’s US payrolls will be the next clear catalyst for the pair.
Educational note: When two currencies face different policy cycles, short-term ranges can still be driven more by the larger economy’s data than by the smaller one’s. Preparing the operational side of a transfer – documentation, beneficiary details and timing confirmation – before a high-profile release such as non-farm payrolls often proves more valuable than attempting to catch a few points of movement once the numbers appear.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Thu 5 Nov (Today) |
09:30 |
GBP |
Construction PMI (Oct) |
43.6 / 46.1 |
46.1 |
★★ |
| Thu 5 Nov (Today) |
12:00 |
GBP |
BoE Interest Rate Decision |
4.00% / 4.00% |
3.75% |
★★★ |
| Thu 5 Nov (Today) |
12:00 |
GBP |
BoE MPC Vote (hike/unchanged) |
8–1 / 7–2 |
– |
★★★ |
| Thu 5 Nov (Today) |
12:30 |
GBP |
Bailey press conference |
– |
– |
★★★ |
| Thu 5 Nov (Today) |
13:30 |
USD |
Initial Jobless Claims |
– / 196k |
194k |
★★ |
| Fri 6 Nov |
10:00 |
EUR |
Retail Sales (Sep) |
– |
– |
★★ |
| Fri 6 Nov |
13:30 |
USD |
Non-farm Payrolls (Oct) |
– / 65k |
29k |
★★★ |
| Fri 6 Nov |
13:30 |
USD |
Unemployment Rate (Oct) |
– |
4.2% |
★★★ |
Events from the past 24 hours are reflected in the pair analyses above.
Conclusion
The BoE’s measured rise to 4%, delivered against a backdrop of energy-driven inflation risks, has been absorbed without fireworks – precisely the sort of orderly outcome markets prefer after weeks of anticipation. The softer dollar that followed the US midterms has provided a modest tailwind, yet Friday’s payrolls remain the week’s final test of that narrative. Beyond the numbers, the practical difference between a transfer that lands cleanly and one that does not often lies in the preparation and communication that surround it rather than in the precise mid-market level at the moment of instruction. Next week’s data will supply fresh context; the operational side of any transfer can be settled well before then.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin