|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
October 30th 2026 |
|
| NEW |
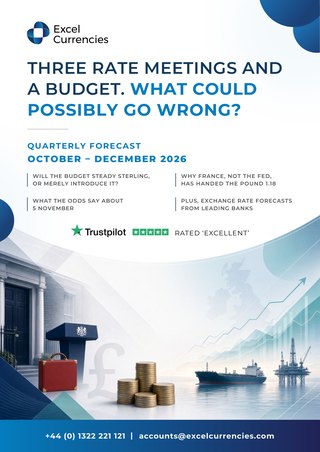
Quarterly Forecast · Q4 2026 |
|
|
| Three rate meetings and a Budget. What could possibly go wrong? |
| October – December 2026 |
| ✓ |
Will the Budget steady sterling, or merely introduce it? |
| ✓ |
Why France, not the Fed, handed the pound 1.18 |
| ✓ |
What the odds say about 5 November |
| ✓ |
Exchange rate forecasts from leading banks |
|
|
|
| Where banks see rates by January 2027 |
GBP/EUR
1.12 – 1.19
€70,000 gap on £1m
|
|
GBP/USD
1.28 – 1.35
$70,000 gap on £1m
|
|
EUR/USD
1.13 – 1.16
$30,000 gap on €1m
|
|
| Four dates that could move your rate |
28 OCT
UK Budget
|
28 OCT
Federal Reserve decision
|
29 OCT
ECB decision
|
5 NOV
Bank of England decision
|
|
|
|
| Free PDF · 11 pages · Bank forecasts, key-event calendar & economic outlook |
| Ranges are the spread of published bank and consensus forecasts, Bloomberg, 5 October 2026. Not dealing rates and not an Excel Currencies forecast. |
|
|
| GBP/EUR tests 1.20 after orderly Budget and central-bank holds |
Today's Key Points
- Sterling firmed against both the euro and dollar over the past 24 hours as the greenback softened on AI-related equity pressure and pre-midterm positioning.
- GBP/EUR pushed toward 1.2000, GBP/USD held above 1.3400, and EUR/USD edged higher after Thursday’s ECB hold.
- The BoJ kept rates unchanged overnight; German Q3 GDP beat forecasts while French GDP contracted, leaving eurozone growth mixed.
- UK Nationwide house prices were flat month-on-month, better than expected, supporting the quieter sterling tone after Wednesday’s Budget.
- Market mood remains cautious but orderly heading into the weekend, with next week’s US midterms, RBA, BoE and payrolls already in view.
- Timing and process continue to matter as much as the rate itself for anyone moving larger sums.
- Even a quiet week moved the numbers: see the table showing the euro difference on a £250,000 transfer – up to €9,700 between the three-month low and this week’s high.
- With the US midterms, the Bank of England and payrolls all next week, know where the banks see sterling heading: download our free Q4 Quarterly Forecast for rate forecasts, the key-event calendar and what the coming events could mean for your transfer.
Market Overview
The past 24 hours have been relatively orderly after a heavy week of central-bank decisions. The dollar softened as tech-stock jitters drove some Treasury buying and as traders trimmed net-long dollar positions ahead of next Tuesday’s US midterms. Sterling led the majors, extending gains after the Bank of Japan held rates and after Thursday’s ECB decision (deposit rate left at 2.50%) failed to deliver a hawkish surprise. Wednesday’s UK Budget from Chancellor John Healey was absorbed without drama; fiscal headroom of £15 billion was broadly as expected and gilts and the pound settled quickly.
Looking ahead, the remainder of the week is light on data after today’s German and eurozone GDP figures and the US Employment Cost Index. Attention is already shifting to next week’s US midterms, the RBA and Bank of England decisions, and Friday’s US payrolls. For anyone transferring money, the lesson of the past few sessions is practical: a rate that looks attractive at 9 a.m. can still be undermined by a delayed payment or unclear instructions that miss the day’s best window. Clean execution has often mattered more than the last tenth of a percent.
GBP/EUR Analysis
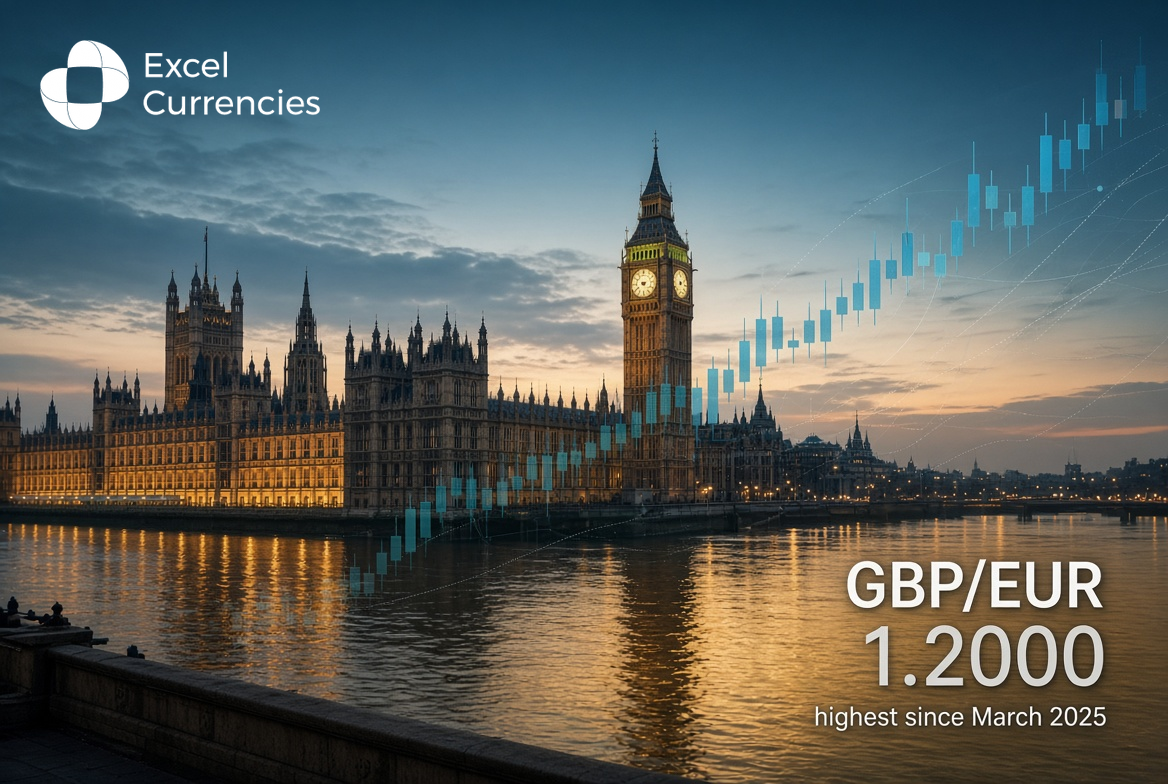
GBP/EUR: €1.1955–€1.2000 | Level: ~1.2000
GBP/EUR has spent the last 24–48 hours grinding higher, testing 1.2000 as the pound outperformed a euro that received only mixed support from the day’s growth numbers. The pair’s 24-hour range ran from 1.1955 to 1.2000, a net gain of roughly 0.24%.
- Dollar softness and sterling’s relative resilience after the Budget provided the main lift.
- German Q3 GDP beat expectations at 0.2% quarter-on-quarter while French GDP contracted, leaving the eurozone picture mixed and limiting euro upside.
- Nationwide house prices were unchanged month-on-month (better than the forecast decline), reinforcing a stable UK housing backdrop.
Educational note: Even in a relatively quiet session the range still produced a material difference on a £250,000 transfer. The market can feel calm while the practical cost of waiting versus acting inside the window remains real; the same principle applies to the week ahead when the midterms and the BoE decision can reopen volatility without much warning.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.2000 |
1.1902 |
€300,000 |
€297,550 |
€2,450 |
| 1 Month |
1.2000 |
1.1664 |
€300,000 |
€291,600 |
€8,400 |
| 3 Months |
1.2000 |
1.1612 |
€300,000 |
€290,300 |
€9,700 |
The numbers show movement is real even when the market feels quiet. Most buyers focus on the rate, yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate with poor support or delays can cost more than a well-timed transfer executed smoothly.
For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so the money arrives exactly when needed, without stress?”
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: $1.3374–$1.3434 | Current: ~1.3400
GBP/USD pushed above 1.3400 and briefly touched 1.3434 as the dollar eased. The 24-hour range was 1.3374–1.3434, a net gain of about 0.37%.
- AI-related equity weakness and pre-midterm position trimming weighed on the dollar.
- Sterling’s post-Budget stability and the better-than-expected Nationwide print added modest support.
- Markets continue to price a Bank of England hike next week, keeping dips relatively shallow.
Educational note: A 60-pip range on GBP/USD is modest by recent standards, yet on a larger transfer it still equates to a noticeable difference in dollars received. Next week’s combination of US political risk and the BoE decision means the quiet Friday range can reopen quickly; having the transfer process already lined up often matters more than waiting for one more pip.
EUR/USD Analysis
EUR/USD: $1.1170–$1.1215 | Current: ~1.1195
EUR/USD edged higher to 1.1195 after the ECB held rates and after mixed eurozone growth data. The 24-hour range ran from 1.1170 to 1.1215, a net gain of roughly 0.13%.
- The ECB’s hold and comments that further hikes remain possible limited downside, while German GDP beat and French GDP missed.
- Dollar softness provided the bulk of the lift; the euro itself showed little independent strength.
- Divergence with sterling is clear: GBP/EUR has made fresh 2026 highs while EUR/USD remains range-bound.
Educational note: When two currencies move for different reasons (sterling on relative UK stability, the euro on mixed growth and a non-committal ECB), the cross can trend even if the dollar pairs look quiet. The week ahead’s US events can reassert dollar direction and compress or expand that divergence; process readiness again tends to matter more than the precise rate on any single day.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Fri 30 Oct (Today) |
Early |
JPY |
BoJ Interest Rate Decision |
Hold / Hold |
– |
★★★ |
| Fri 30 Oct (Today) |
07:00 |
GBP |
Nationwide HPI (MoM) |
0.0% / -0.1% |
-0.3% |
★★ |
| Fri 30 Oct (Today) |
09:00 |
EUR |
German GDP (Q3, flash) |
0.2% / 0.1% |
0.3% |
★★★ |
| Fri 30 Oct (Today) |
10:00 |
EUR |
Eurozone GDP (Q3, flash) |
0.4% / 0.2% |
0.6% |
★★★ |
| Fri 30 Oct (Today) |
12:30 |
USD |
Employment Cost Index (Q3) |
– / 0.8% |
0.9% |
★★ |
| Fri 30 Oct (Today) |
13:00 |
EUR |
German CPI (flash) |
– |
– |
★★★ |
Events from the past 24 hours are reflected in the pair analyses above.
Conclusion
Sterling has enjoyed a tidy week, the Budget passed without fireworks, and the dollar has taken a modest breather ahead of the midterms. The euro remains the relative underperformer, which has helped GBP/EUR test fresh highs. None of this guarantees a quiet weekend or a predictable Monday; markets have a habit of discovering fresh reasons to move just as everyone else is thinking about the weekend. For those who still need to move money, the practical edge continues to lie in having the process already sorted rather than in hoping the rate stays exactly where it is while the paperwork catches up. Next week’s political and central-bank diary will test that approach soon enough.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin