|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
November 3rd 2026 |
|
| NEW |
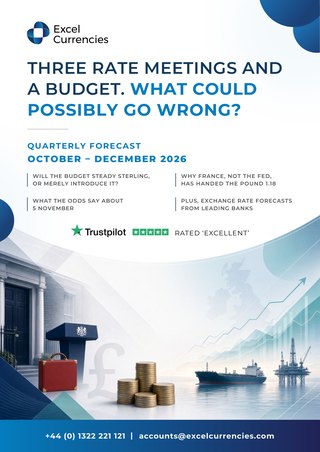
Quarterly Forecast · Q4 2026 |
|
|
| Three rate meetings and a Budget. What could possibly go wrong? |
| October – December 2026 |
| ✓ |
Will the Budget steady sterling, or merely introduce it? |
| ✓ |
Why France, not the Fed, handed the pound 1.18 |
| ✓ |
What the odds say about 5 November |
| ✓ |
Exchange rate forecasts from leading banks |
|
|
|
| Where banks see rates by January 2027 |
GBP/EUR
1.12 – 1.19
€70,000 gap on £1m
|
|
GBP/USD
1.28 – 1.35
$70,000 gap on £1m
|
|
EUR/USD
1.13 – 1.16
$30,000 gap on €1m
|
|
| Four dates that could move your rate |
28 OCT
UK Budget
|
28 OCT
Federal Reserve decision
|
29 OCT
ECB decision
|
5 NOV
Bank of England decision
|
|
|
|
| Free PDF · 11 pages · Bank forecasts, key-event calendar & economic outlook |
| Ranges are the spread of published bank and consensus forecasts, Bloomberg, 5 October 2026. Not dealing rates and not an Excel Currencies forecast. |
|
|
| GBP holding steady as markets price a 4.00% Bank Rate |
Today's Key Points
- Sterling held steady overnight after Australia’s central bank delivered a widely expected 25bp hike to 4.85% on a split 6-3 vote.
- GBP/EUR traded a tight 24-hour range of roughly 16 pips with a small net gain; GBP/USD and EUR/USD were similarly contained.
- Market attention has already shifted to Thursday’s Bank of England decision, where a rise to 4.00% is almost fully priced.
- Today’s main scheduled release is US JOLTS job openings at 15:00 GMT; factory orders follow the same hour.
- US midterm results will trickle in overnight, adding a layer of political noise but limited immediate FX impact so far.
- Eurozone flash CPI on Wednesday and US payrolls on Friday remain the other clear high-impact markers for the week.
- Ranges have been orderly; the larger practical difference for many buyers continues to lie in process and timing rather than the last few basis points of rate.
- Even a quiet market moves the numbers: see the table showing the euro difference on a £250,000 transfer – up to €10,050 between the three-month low and the recent high.
- With the Bank of England on Thursday and US payrolls on Friday, know where the banks see sterling heading: download our free Q4 Quarterly Forecast for rate forecasts, the key-event calendar and what this week’s decisions could mean for your transfer.
Market Overview
The past 24 hours have been relatively subdued once the Reserve Bank of Australia’s overnight decision was digested. A 25bp rise to an 18-year high of 4.85% arrived as expected, though the 6-3 split and the removal of explicit forward-hike language left a slightly less hawkish aftertaste. Sterling and the euro both held their ground against a broadly steady dollar.
Looking ahead, the week is dominated by the Bank of England on Thursday (consensus firmly for a first hike of the cycle to 4.00%) and Friday’s US employment report. UK political noise remains secondary for now; the late-October Budget continues to be absorbed rather than generating fresh market-moving headlines. In practice, the difference between a transfer executed at the top of a quiet range and one delayed by paperwork or incomplete instructions can easily exceed the cost of a few pips of rate movement – especially when the receiving party is waiting on a fixed completion date.
GBP/EUR Analysis
GBP/EUR: ~€1.1985–€1.1995 | 24-hour range: c.16 pips
Sterling has spent the last day and a half oscillating in a narrow band against the euro, finishing modestly higher after the RBA decision failed to spark broader risk aversion. The pair has been content to mark time while markets wait for clearer signals from Threadneedle Street and the eurozone inflation print.
- The overnight RBA hike to 4.85% (6-3) removed one source of uncertainty without generating lasting sterling weakness.
- Limited fresh UK data; attention is already concentrated on Thursday’s MPC decision and accompanying Monetary Policy Report.
- Eurozone flash CPI (Wednesday) is the nearest euro-specific catalyst that could shift relative pricing.
Educational note: When a rate is already heavily priced, the residual volatility often arrives in the shape of the vote split and the language around future moves rather than the headline decision itself. For a buyer transferring a fixed sterling amount into euros this week, the practical variable is less the difference between 1.1985 and 1.1995 and more whether instructions, documentation and cut-off times allow the transfer to clear on the day the funds are actually needed. A smooth process at a mid-range rate frequently outperforms a theoretically better rate that arrives a day late.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.2016 |
1.1933 |
€300,400 |
€298,325 |
€2,075 |
| 1 Month |
1.2016 |
1.1785 |
€300,400 |
€294,625 |
€5,775 |
| 3 Months |
1.2016 |
1.1614 |
€300,400 |
€290,350 |
€10,050 |
The numbers show movement is real even when the market feels quiet. Most buyers focus on the rate, yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate with poor support or delays can cost more than a well-timed transfer executed smoothly.
For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so the money arrives exactly when needed, without stress?”
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: $1.3396–$1.3426 | Net change: negligible
Cable has traded with similar restraint, posting a 24-hour range of approximately 1.3396–1.3426 and a negligible net change. The dollar has been steady rather than directional ahead of today’s US labour-market data and the ongoing midterms.
- The RBA decision provided a brief global rates reference but did not alter the broader dollar tone.
- US JOLTS (15:00 GMT) is the first meaningful US labour print of the week; a soft reading would be the more market-relevant surprise.
- Thursday’s BoE decision remains the clearer sterling-specific catalyst; a 7-2 vote is the widely expected split.
Educational note: Dollar pairs frequently react more to the second-order details – revisions, wage growth, participation – than to the headline number once the market has already positioned for a known event. For anyone converting sterling into dollars this week, the same logic applies to process: a transfer that clears cleanly on the day of a BoE or payrolls release often matters more than capturing the absolute extreme of a 30-pip range.
EUR/USD Analysis
EUR/USD: $1.1149–$1.1237 | Net change: little
The euro has likewise been range-bound against the dollar, with a 24-hour span of roughly 1.1149–1.1237 and little net movement. Relative calm prevails ahead of Wednesday’s flash CPI and Friday’s US employment figures.
- The eurozone inflation print on Wednesday is the nearest euro-specific data point; energy and core readings will be watched for signs of persistence.
- US midterms and JOLTS today are secondary for the pair unless they produce a clear risk-off or risk-on shift.
- Divergence between the BoE (expected to hike) and a still data-dependent Fed remains the medium-term theme, though it is not yet driving sharp moves.
Educational note: When two currencies face high-impact events on consecutive days, the larger practical risk for a transfer is often a temporary widening of spreads or a short delay in settlement rather than a permanent directional shift. Clean documentation and confirmed cut-offs tend to protect more value than attempting to fine-tune the exact minute of execution.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Tue 3 Nov (Today) |
15:00 |
USD |
JOLTS Job Openings |
– / 7.1M |
7.08M |
★★ |
| Tue 3 Nov (Today) |
15:00 |
USD |
Factory Orders m/m |
– / 1.2% |
0.1% |
★★ |
| Wed 4 Nov |
10:00 |
EUR |
CPI y/y (Flash) |
– / ~3.8–3.9% |
3.8% |
★★★ |
| Wed 4 Nov |
13:15 |
USD |
ADP Employment |
– / ~60–70k |
– |
★★ |
| Wed 4 Nov |
15:00 |
USD |
ISM Services PMI |
– |
– |
★★★ |
| Thu 5 Nov |
12:00 |
GBP |
BoE Bank Rate |
– / 4.00% |
3.75% |
★★★ |
| Thu 5 Nov |
13:30 |
USD |
Initial Jobless Claims |
– |
~194k |
★★ |
| Fri 6 Nov |
13:30 |
USD |
Nonfarm Payrolls |
– / ~40–65k |
+29k |
★★★ |
| Fri 6 Nov |
13:30 |
USD |
Unemployment Rate |
– / 4.2% |
4.2% |
★★★ |
Events from the past 24 hours are reflected in the pair analyses above.
Conclusion
The market has absorbed the RBA’s split hike without drama and is now quietly positioning for Thursday’s Bank of England decision and Friday’s US payrolls. Sterling and the euro have both held their recent ranges against a steady dollar, while UK political developments remain in the background rather than the foreground. In a week of known events and contained volatility, the practical edge continues to rest with those who treat timing, documentation and execution as carefully as the rate itself.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin