• Home
  • Blog
  • Heres Your Daily Currency Update 28 October 2026

Here's your Daily Currency Update – 28 October 2026

logo 22year
Daily Market Report
Currency insight from
Excel Currencies
banner1
Karl
Written by Karl Daly
October 28th 2026
NEW Quarterly Forecast · Q4 2026
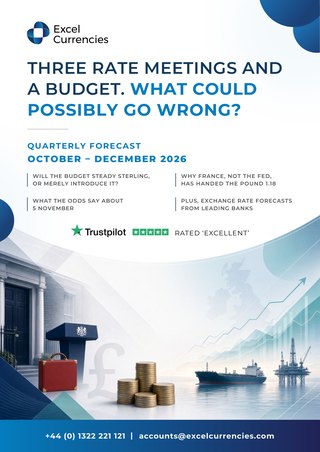
Excel Currencies Quarterly Forecast, October to December 2026
Three rate meetings and a Budget. What could possibly go wrong?
October – December 2026
✓ Will the Budget steady sterling, or merely introduce it?
✓ Why France, not the Fed, handed the pound 1.18
✓ What the odds say about 5 November
✓ Exchange rate forecasts from leading banks
Where banks see rates by January 2027
GBP/EUR
1.12 – 1.19
€70,000 gap on £1m
  GBP/USD
1.28 – 1.35
$70,000 gap on £1m
  EUR/USD
1.13 – 1.16
$30,000 gap on €1m
Four dates that could move your rate
28 OCT
UK Budget
28 OCT
Federal Reserve decision
29 OCT
ECB decision
5 NOV
Bank of England decision
Download the Q4 Forecast  ↓
Free PDF · 11 pages · Bank forecasts, key-event calendar & economic outlook
Ranges are the spread of published bank and consensus forecasts, Bloomberg, 5 October 2026. Not dealing rates and not an Excel Currencies forecast.
Budget Landed, Fed Next: Sterling Soft, Markets Cautious
Today's Key Points
  • Sterling has edged lower over the past 24 hours as markets weighed a firm dollar and the UK Budget against generally solid US data yesterday.
  • US consumer confidence and durable goods figures came in better than expected, supporting the dollar while the euro held a narrow range.
  • Chancellor John Healey delivered the Autumn Budget at midday, emphasising energy bill relief, a £15bn fiscal headroom, and no major tax rises on working people; gilts remained relatively stable.
  • The Federal Reserve is expected to hold rates at 3.75–4.00% this evening, with attention on Chair Kevin Warsh’s comments about the path ahead.
  • Thursday brings US Q3 GDP and core PCE alongside the ECB decision, where a hold at 2.50% is widely anticipated.
  • Overall mood is watchful: fiscal credibility and central-bank patience are the main themes.
  • Budget day volatility in numbers: see the table showing the euro difference on a £250,000 transfer – up to €7,825 between the three-month low and the recent high.
  • With the Fed tonight and the ECB tomorrow, know where the banks see sterling heading: download our free Q4 Quarterly Forecast for rate forecasts, the key-event calendar and what today’s Budget could mean for your transfer.
Market Overview

The past 24 hours have been more about positioning than fireworks. Sterling softened modestly against both the euro and the dollar as traders digested stronger-than-forecast US consumer confidence (91.7) and durable goods orders from Tuesday, which kept the greenback firm. The UK Budget, delivered by Chancellor John Healey around 12:30 UK time, focused on household energy relief (scrapping gas standing charges and extending the electricity VAT cut), a projected fiscal headroom of £15bn in 2029-30, and growth forecasts of 1.2% this year. Gilts held relatively steady, suggesting the market saw the package as broadly consistent with earlier expectations of limited headroom and no large tax surprises on labour income.

Looking ahead, tonight’s Federal Reserve decision (widely expected to be a hold after September’s hike) and Thursday’s combination of US Q3 GDP, core PCE and the ECB meeting will dominate. Timing around these releases often proves more consequential than the spot rate itself: a delayed or incomplete transfer instruction can miss a brief window of liquidity or a post-event move that a well-prepared process would capture cleanly.

Key Budget measures
  • Gas standing charges to be scrapped from next year for around 23 million households, saving roughly £45–£108 on a typical bill.
  • VAT cut on electricity bills extended until July, taking about £50 a year off the average annual bill; fuel duty freeze also extended to July 2027.
  • Fiscal headroom set at £15bn in 2029-30, rising to £22bn in 2030-31; OBR growth forecast 1.2% this year, 1% next year, then 1.6–1.8% in subsequent years.
  • Borrowing to fall from 4.4% of GDP to 4.2% this year, with the deficit to be eliminated within three years; debt projected to edge down from 83.2% of GDP.
  • Extra funding (around £20bn over several years) for the National Wealth Fund and British Business Bank to support energy, defence, AI and infrastructure projects.
  • National living wage to rise by nearly 4%; emphasis on “breathing space” for households and businesses without major tax rises on working people.
GBP/EUR Analysis

GBP/EUR: €1.1821–€1.1932 | Level: ~1.1938 (0.8377)

Sterling has drifted lower against the euro over the last day or so, moving from the upper end of its recent range toward 1.1938 (0.8377) as Budget caution and a firmer dollar limited appetite for the pound. The pair’s 24-hour range ran from roughly 1.1937 to 1.1962, a net decline of about 0.0022.

  • Stronger US data yesterday supported the dollar and, by extension, capped euro strength relative to sterling.
  • The Budget’s emphasis on energy relief and a £15bn headroom figure was largely anticipated, producing little fresh directional impulse once the speech concluded.
  • Euro-area sentiment indicators earlier in the week remained soft, but not weak enough to drive a clear break lower in the cross.
Educational note: When fiscal and monetary events cluster, the exchange rate itself is only part of the cost. The difference between transferring at the high or low of a week’s range can amount to several thousand euros on a typical property purchase, yet the larger practical variable is often whether the funds are ready and the process is clear before the event window. Over the rest of the week the ECB decision and US data will test whether the euro can sustain any relative strength; a smooth, timed transfer still tends to matter more than catching the absolute peak.
PROPERTY BUYER SPOTLIGHT
Timing, Range & the Bigger Picture
 

This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.

Period High Low £250k at High £250k at Low Difference
1 Week 1.1962 1.1902 €299,050 €297,550 €1,500
1 Month 1.1963 1.1699 €299,075 €292,475 €6,600
3 Months 1.1963 1.1650 €299,075 €291,250 €7,825

The numbers show movement is real even when the market feels quiet. Most buyers focus on the rate, yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate with poor support or delays can cost more than a well-timed transfer executed smoothly.

For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so the money arrives exactly when needed, without stress?”

Want to see a different amount or timeline? try our useful calculator...

Try Calculator Here

GBP/USD Analysis

GBP/USD: $1.3155–$1.3278 | Current: ~1.3288

The pound has softened against the dollar over the past 24 hours, trading near 1.3288 after a range of 1.3272–1.3312 and a net decline of roughly 0.0018. The move reflects both the Budget’s lack of positive surprise and the support the dollar received from Tuesday’s US figures.

  • US consumer confidence and durable goods both beat forecasts, reinforcing the view that the Fed can afford to pause tonight.
  • Sterling’s pre-Budget drift was orderly; the speech itself did not trigger a sharp reaction once the main numbers were known.
  • Broader dollar strength ahead of the FOMC has limited any recovery attempt.
Educational note: In a week that contains both a UK fiscal event and a US rate decision, the practical cost of a transfer is shaped as much by when instructions are given as by the mid-market rate. A clean process that allows funds to move promptly after a data release or press conference can capture a better effective rate than waiting for a theoretically better level that never quite arrives. Thursday’s US GDP and PCE will give a further reading on whether the dollar’s recent firmness has further to run.

EUR/USD Analysis

EUR/USD: ~1.1136

The euro has edged slightly higher against the dollar over the last day, sitting near 1.1136 within a tight 1.1113–1.1137 range and posting a modest net gain of about 0.0010. The pair remains constrained by the approaching ECB meeting and the Fed’s expected hold.

  • Tuesday’s solid US data limited upside for the euro, while softer euro-area surveys earlier in the week prevented a clearer recovery.
  • Markets price a high probability that the ECB will leave the deposit rate at 2.50% on Thursday.
  • Divergence between a patient Fed and a data-dependent ECB is the main near-term theme.
Educational note: When two major central banks meet within 24 hours, the cross can see short bursts of volatility that reverse quickly once the statements are absorbed. The value for many users lies less in predicting the direction and more in ensuring that any required transfer is executed cleanly around the known release times, so that the practical outcome is not undermined by process delays. Friday’s euro-area GDP and German inflation figures will provide the next test of relative momentum.

Weekly Economic Calendar

Date Time (UK) Currency Event Actual / Forecast Previous Imp.
Wed 28 Oct (Today) 12:30 GBP Autumn Budget / Forecast Statement – – ★★★
Wed 28 Oct (Today) 13:45 CAD BoC Rate Decision – / 2.50% 2.25% ★★★
Wed 28 Oct (Today) 18:00 USD Fed Interest Rate Decision – / 4.00% 4.00% ★★★
Thu 29 Oct 09:30 GBP Mortgage Approvals / Consumer Credit – – ★★
Thu 29 Oct 12:30 USD Q3 GDP Advance & Core PCE – – ★★★
Thu 29 Oct 13:15 EUR ECB Rate Decision – / 2.50% 2.50% ★★★
Fri 30 Oct 10:00 EUR Eurozone Q3 GDP – – ★★★
Fri 30 Oct 13:00 EUR German CPI / HICP – – ★★★

Events from the past 24 hours are reflected in the pair analyses above.

Conclusion

The Budget has landed without major market disruption and the Fed is expected to stand pat this evening, leaving Thursday’s US growth and inflation numbers plus the ECB as the remaining clear catalysts. Sterling’s modest weakness and the euro’s narrow range reflect a market that is informed but not yet decisive. Over the rest of the week the practical difference for many will still come down to having the process ready rather than waiting for a perfect rate that may not appear. A dry week for drama so far; the data still has the last word.

This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.