|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
September 23rd 2026 |
|
| Europe beat the survey, the dollar beat Europe — GBP/USD near 1.328 |
Today's Key Points
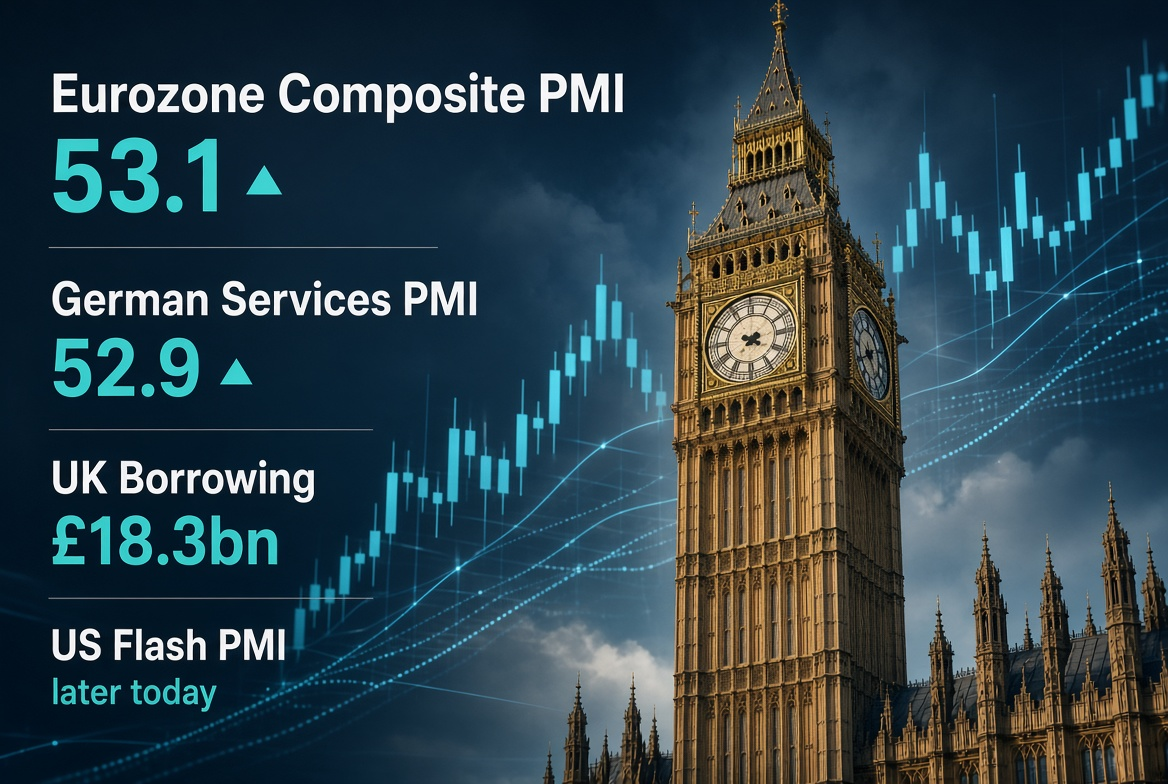
- Sterling slipped against the dollar after Tuesday’s larger-than-expected UK borrowing print, while holding almost flat versus the euro.
- Eurozone flash PMIs this morning beat forecasts, led by a rebound in German and French services.
- UK flash PMIs were due at 09:30 BST; markets are still absorbing that print alongside yesterday’s fiscal news.
- The dollar is firmer ahead of this afternoon’s US flash PMI (14:45 UK).
- Mood: cautious rather than panicked — fiscal nerves at home, firmer activity data on the Continent.
- Rest of the week: US current account and new home sales Thursday; durable goods and Michigan sentiment Friday, plus Bank of England Governor Bailey speaking.
- Current mid-market ranges: GBP/EUR €1.1567–€1.1634 | GBP/USD $1.3201–$1.3303.
- Live mid-market: GBP/EUR 1.1652 (0.8582) · GBP/USD 1.3312 · EUR/USD 1.1425.
- New in this report: Property Buyer Spotlight – see the real 1-week, 1-month and 3-month high/low ranges and what they mean for a £250,000 transfer.
Market Overview
The past 24 hours split neatly in two. On Tuesday the Office for National Statistics reported public-sector net borrowing of £18.3 billion for August, well above the roughly £15.7 billion expected and £8.1 billion above the Office for Budget Responsibility’s year-to-date path. That kept gilt yields supported and left sterling on the back foot versus the dollar. This morning the story shifted to activity surveys: the eurozone composite flash PMI jumped to 53.1 from 52.0 (forecast 51.7), with German services leaping to 52.9 from 49.7. UK flash PMIs followed at 09:30. Politically, the October 28 Budget is now the dominant domestic theme. Chancellor John Healey faces a tighter fiscal arithmetic after the borrowing miss, while banks have publicly warned that a windfall tax would push activity away from London. Oil’s retreat from recent highs has taken some heat out of imported-inflation fears, but has not removed the Budget question. Thursday and Friday’s US data will decide whether the dollar’s bid extends.
GBP/EUR Analysis
GBP/EUR: €1.1567–€1.1634 | Level: ~1.1652 (0.8582)
- Cross-Channel trade was the quiet pair of the session. Eurozone surveys printed stronger than sterling-watchers had allowed for, yet the pound barely gave ground because the euro itself was capped by a firmer dollar.
- Tuesday’s CBI industrial-trends survey offered a modest offset: the total order-book balance improved to −9 from −25, the best reading since July 2023 and far above the −34 expected.
- Eurozone composite PMI 53.1 vs 51.7 expected; services 53.0 vs 51.4. German composite 53.8 vs 51.8; French services 51.4 vs 48.3.
- UK borrowing overshoot remains the sterling-specific drag. Range compression overnight suggests participants are waiting for US PMI confirmation.
Educational note: Flash PMIs are first-look surveys covering roughly three-quarters of the final sample. A surprise in services often moves EUR crosses more than a manufacturing miss of similar size, because services dominate euro-area GDP. That is why this morning’s German and French services beats mattered even though German manufacturing slipped to 53.8. Into Thursday’s German Ifo and Friday’s UK-related speeches, the same rule applies: activity breadth usually outranks a single factory number.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.1682 |
1.1619 |
€292,050 |
€290,475 |
€1,575 |
| 1 Month |
1.1691 |
1.1631 |
€292,275 |
€290,775 |
€1,500 |
| 3 Months |
1.1809 |
1.1587 |
€295,225 |
€289,675 |
€5,550 |
The numbers show that movement is real, even when the market feels quiet. Most buyers naturally focus on the rate itself. Yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate achieved with poor support or unexpected delays can easily cost more than a well-timed transfer executed smoothly.
For early-stage property buyers — and businesses moving larger sums — the real question is rarely just “what is the rate today?” It is “who will help navigate the timing, paperwork and practicalities so the money arrives exactly when needed, without stress?”
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: $1.3201–$1.3303 | Current: ~1.3312
- This was the pair that carried the fiscal story. After the August borrowing miss, sterling opened the London session nearer 1.334 and drifted toward 1.330 as the dollar stayed bid.
- UK PSNB £18.3bn vs ~£15.7bn expected; year-to-date £8.1bn above the OBR path. Debt-interest costs in August were the highest for that month in the ONS series.
- Intraday low near 1.3301, high near 1.3352 in the London morning book. Dollar strength is broad, not sterling-specific — EUR/USD also eased.
- This afternoon’s US flash PMI is the next scheduled test; Budget-date positioning is already visible in gilt and sterling option markets.
Educational note: Public-sector borrowing surprises move sterling through two channels at once: the expected path of gilt supply, and the expected size of any tax package. When the figure overshoots, markets often mark the pound down against the dollar first because that pair is the more liquid “fiscal barometer.” The euro cross can lag if European data are simultaneously improving, which is exactly the pattern of the past 24 hours.
EUR/USD Analysis
EUR/USD: ~1.1425
- The euro enjoyed a better data morning than a better tape. Composite activity at 53.1 and a services rebound in both Germany and France should, in isolation, have lifted the single currency. Instead EUR/USD slipped as the dollar absorbed the news.
- Eurozone services 53.0 vs 51.4; manufacturing 52.7 vs 52.6. Manufacturing in Germany eased to 53.8 versus 54.1 expected, so the beat was services-led.
- Pair remains near recent lows even after the PMI beat. Divergence versus GBP/EUR: the pound is holding its euro rate while losing ground to the dollar.
Educational note: When a currency’s home data beat and the pair still falls, the move is usually coming from the other side of the quote. That is a useful filter for the rest of the week: treat US prints as the swing factor for EUR/USD, and treat European surveys as the swing factor for GBP/EUR.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Tue 22 Sep |
07:00 |
GBP |
Public Sector Net Borrowing (Aug) |
£18.3bn / £15.7bn |
£15.4bn |
★★ |
| Tue 22 Sep |
11:00 |
GBP |
CBI Industrial Trends – Orders |
−9 / −34 |
−25 |
★★ |
| Wed 23 Sep (Today) |
08:15 |
EUR |
France Flash Services / Mfg PMI |
51.4 / 50.3 / 48.3 / 50.9 |
48.0 / 51.1 |
★★★ |
| Wed 23 Sep (Today) |
08:30 |
EUR |
Germany Flash Services / Mfg PMI |
52.9 / 53.8 / 49.9 / 54.1 |
49.7 / 54.3 |
★★★ |
| Wed 23 Sep (Today) |
09:00 |
EUR |
Eurozone Flash Composite / Services / Mfg |
53.1 / 53.0 / 52.7 / 51.7 / 51.4 / 52.6 |
52.0 / 51.6 / 52.7 |
★★★ |
| Wed 23 Sep (Today) |
09:30 |
GBP |
UK Flash Composite / Services / Mfg PMI |
Due / 52.0 / 52.0 / 51.5 |
52.5 / 52.5 / 51.7 |
★★★ |
| Wed 23 Sep (Today) |
14:45 |
USD |
US Flash Composite / Services / Mfg PMI |
– / 55.2 / 55.8 / 53.6 |
56.0 / 56.5 / 53.9 |
★★★ |
| Thu 24 Sep |
09:00 |
EUR |
German Ifo Business Climate |
– / 89.1 |
88.8 |
★★ |
| Thu 24 Sep |
13:30 |
USD |
Initial Jobless Claims / Current Account |
– / 201k / −$255bn |
196k / −$226.8bn |
★★ |
| Thu 24 Sep |
15:00 |
USD |
New Home Sales (Aug) |
– / 0.62m |
0.607m |
★★ |
| Fri 25 Sep |
09:15 |
GBP |
BoE Governor Bailey Speech |
– |
– |
★★ |
| Fri 25 Sep |
13:30 |
USD |
Durable Goods Orders (Aug P) |
– / −0.4% |
+1.1% |
★★★ |
| Fri 25 Sep |
15:00 |
USD |
U. of Michigan Sentiment (Sep F) |
– |
– |
★★ |
Conclusion
Sterling’s last 24 hours were a study in two speeds: almost unchanged against the euro after a strong Continental PMI morning, softer against the dollar after a clear UK fiscal miss. That combination leaves the Budget of 28 October as the medium-term anchor and US data as the near-term swing. Thursday’s claims, current account and new-home sales, then Friday’s durable goods and Bailey’s remarks, will fill in the rest of the week’s picture. None of those items need to be dramatic to matter; in a narrow range, small confirmed surprises are enough to reset the tone. For property buyers and businesses moving sizeable sums, the rate on the screen remains only one part of the job: the transfer still has to land on the right day, with the paperwork intact and no last-minute scramble.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin