|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
October 23rd 2026 |
|
| NEW |
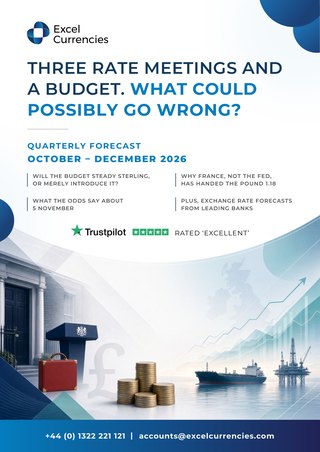
Quarterly Forecast · Q4 2026 |
|
|
| Three rate meetings and a Budget. What could possibly go wrong? |
| October – December 2026 |
| ✓ |
Will the Budget steady sterling, or merely introduce it? |
| ✓ |
Why France, not the Fed, handed the pound 1.18 |
| ✓ |
What the odds say about 5 November |
| ✓ |
Exchange rate forecasts from leading banks |
|
|
|
| Where banks see rates by January 2027 |
GBP/EUR
1.12 – 1.19
€70,000 gap on £1m
|
|
GBP/USD
1.28 – 1.35
$70,000 gap on £1m
|
|
EUR/USD
1.13 – 1.16
$30,000 gap on €1m
|
|
| Four dates that could move your rate |
28 OCT
UK Budget
|
28 OCT
Federal Reserve decision
|
29 OCT
ECB decision
|
5 NOV
Bank of England decision
|
|
|
|
| Free PDF · 11 pages · Bank forecasts, key-event calendar & economic outlook |
| Ranges are the spread of published bank and consensus forecasts, Bloomberg, 5 October 2026. Not dealing rates and not an Excel Currencies forecast. |
|
|
| GBP/EUR remains above 1.19: retail sales miss, PMI strength, Budget in five days |
Today's Key Points
- GBP/EUR is trading near 1.1945–1.1946, with an intraday high of 1.1949, above the 1.19 upper end of major banks’ published quarterly forecasts for Q4.
- September retail sales volumes fell 0.4% m/m (vs –0.1% expected) after a revised +0.7% in August.
- GfK consumer confidence dropped 11 points to –24, the sharpest monthly fall since the early pandemic.
- Flash October composite PMI beat expectations at 53.1; a further BoE hike next month is largely priced in ahead of the 28 October Budget.
- Current mid-market ranges: GBP/EUR €1.1821–€1.1945 | GBP/USD $1.3233–$1.3351. Spot: GBP/EUR 1.1945 (0.8372), GBP/USD ~1.3390, EUR/USD ~1.1210.
- See exactly what the move above 1.19 is worth: view the table showing the euro difference on a £250,000 transfer – up to €8,325 between the three-month low and this week’s high.
- Want to know where the major banks see sterling heading next? Download our free Q4 Quarterly Forecast for bank rate forecasts, the key event calendar and what the Budget could mean for your transfer.
Market Overview
Sterling has held near multi-month highs against the euro over the past two sessions, even after this morning’s softer consumer data. Retail sales volumes declined 0.4% in September, more than the consensus –0.1% fall, as warm weather weighed on autumn clothing demand and supermarket volumes eased after a strong August. Overnight, the GfK consumer confidence index fell 11 points to –24 from –13, well below forecasts around –15 and the largest monthly drop since April 2020.
These readings have not reversed the underlying bid in the pound. The flash S&P Global PMI composite rose to 53.1 in October from around 52.0 previously, above the 51.8 consensus and the strongest reading in eight months, with new orders accelerating and employment returning to modest growth. Combined with Wednesday’s 3.5% CPI print, this has reinforced the view that any further Bank of England tightening in November is already largely discounted. The result is that GBP/EUR remains above the 1.19 level that formed the upper bound of the largest banks’ published quarterly forecasts for the end of the year.
GBP/EUR Analysis
GBP/EUR: €1.1821–€1.1945 | Level: ~1.1945 (0.8372)
The pair is trading at 1.1945 (0.8372), having briefly touched 1.1949. Over the past two sessions the range has been contained between roughly 1.1911 and 1.1949. The sustained move through 1.19 is material because it sits above the peak many major banks had set in their quarterly outlooks. For buyers of euro-denominated property looking toward completions into early 2027, this is the first period the rate has held above that consensus ceiling.
Volatility over the two days has been moderate at roughly 0.3%. The retail-sales miss and confidence shock have not been enough to reverse the bid, consistent with the stronger PMI data and the pricing of further BoE action. Markets continue to treat the November hike as largely baked in; the more immediate event risk is the Budget on Wednesday.
- Key resistance sits just above 1.1950.
- Support is seen near 1.1900–1.1910, the area that contained the pair earlier in the week.
- The 28 October Budget and the 5 November BoE decision are the next clear catalysts.
Educational note: When a currency pair moves above the upper end of widely published quarterly forecasts, the euro proceeds available on a sterling-funded purchase increase relative to the path most analysts had pencilled in. The table below quantifies the difference for a £250,000 commitment using observed highs and lows from daily data.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.1949 |
1.1827 |
€298,725 |
€295,675 |
€3,050 |
| 1 Month |
1.1949 |
1.1699 |
€298,725 |
€292,475 |
€6,250 |
| 3 Months |
1.1949 |
1.1616 |
€298,725 |
€290,400 |
€8,325 |
Figures are illustrative mid-market calculations based on observed ranges. They are not forecasts. Events from the past 48 hours are reflected in the pair analyses above.
At levels above the major banks’ quarterly forecast high, many clients choose to map a specific purchase or staged-transfer approach rather than leave the outcome entirely to subsequent market moves. If the current rate is relevant to a timeline you have in mind—particularly for a property completion into the first quarter of next year—reply to this email or contact your account manager. We can outline the practical options without any obligation.
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: $1.3233–$1.3351 | Current: ~1.3390
Cable is trading near 1.3390. The two-day range has been approximately 1.3355–1.3419. Sterling has retained most of its recent gains despite the retail sales disappointment, supported by the PMI beat and the broader pricing of further BoE tightening. The pair remains inside the broader October range of roughly 1.32–1.35.
Volatility has stayed low-to-moderate. The dollar has been relatively steady, with attention shifting toward the Federal Reserve decision on 28 October and any signals from the UK Budget on the same day that could alter BoE expectations.
- Resistance is seen near 1.3420–1.3450.
- Support lies around 1.3350, with a deeper floor near 1.3300.
- The clearest near-term risk is any softening of BoE hike expectations after the Budget.
Educational note: Sterling’s resilience against the dollar this week has been driven more by UK rate expectations than by outright dollar weakness. A Budget that is perceived as growth-friendly or inflation-sticky could keep cable supported; a more cautious fiscal stance could quickly reverse the recent gains.
EUR/USD Analysis
EUR/USD: ~1.1210
The euro is trading around 1.1210 against the dollar. The two-day range has been roughly 1.1185–1.1256. Eurozone flash PMIs were mixed and softer than the UK readings, leaving the single currency slightly on the defensive ahead of the ECB decision later this month and the Federal Reserve meeting on 28 October.
Volatility has remained contained. The pair has tracked broader dollar moves more than any single eurozone release, with limited impetus from the softer European data.
- Resistance sits near 1.1250–1.1280.
- Support is seen around 1.1180, with a firmer floor near 1.1150.
- The ECB and Fed decisions next week are the main drivers to watch.
Educational note: EUR/USD has lacked a clear directional catalyst this week, oscillating inside a relatively tight range. With both central banks meeting in the coming days, the pair is more likely to take its cue from relative rate expectations than from the latest PMI prints.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Wed 21 Oct |
07:00 |
GBP |
CPI (YoY) |
3.5% / 3.4% |
3.1% |
★★★ |
| Fri 23 Oct (Today) |
00:01 |
GBP |
GfK Consumer Confidence |
–24 / –15 |
–13 |
★★ |
| Fri 23 Oct (Today) |
07:00 |
GBP |
Retail Sales (MoM) |
–0.4% / –0.1% |
0.7% |
★★★ |
| Fri 23 Oct (Today) |
09:30 |
GBP |
Flash Composite PMI |
53.1 / 51.8 |
52.0 |
★★★ |
| Fri 23 Oct (Today) |
14:45 |
USD |
Flash PMI |
– |
– |
★★ |
Next high-impact UK event: Autumn Budget, Wednesday 28 October.
Conclusion
Sterling’s ability to hold above 1.19 against the euro after a clear retail-sales miss and a sharp drop in confidence shows how much of the near-term rate path is already discounted. The three-month improvement in euro proceeds on a £250,000 sterling purchase is now material relative to levels earlier in the quarter. With the Budget only five days away and the Bank of England decision a week after that, the window for levels above the banks’ quarterly forecast high is open but subject to headline risk. If this rate is relevant to a purchase or transfer you are planning into early 2027, a short conversation with your account manager can clarify the practical options before the next set of decisions arrives. On a Friday, at least the markets are closing for the weekend—though the calendar is not.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin