• Home
  • Blog
  • Heres Your Daily Currency Update 22 September 2026

Here's your Daily Currency Update – 22 September 2026

logo 22year
Daily Market Report
Currency insight from
Excel Currencies
banner1
Karl
Written by Karl Daly
September 22nd 2026
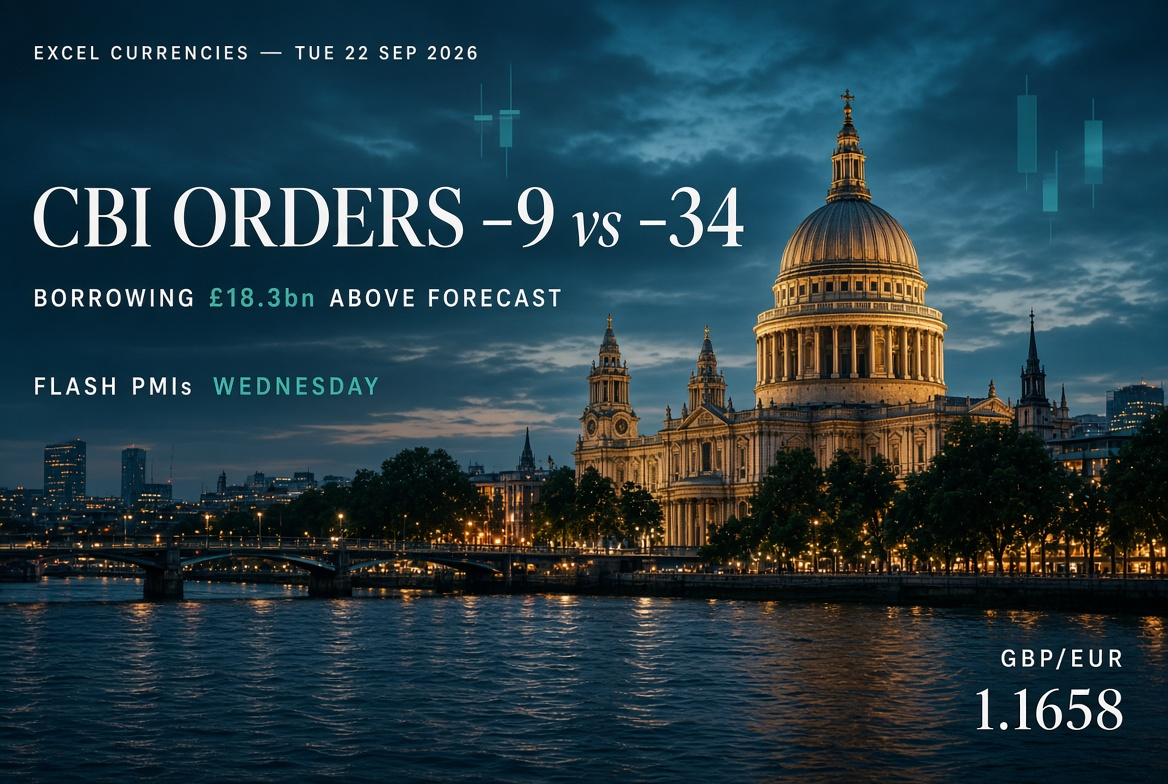
Best factory orders since 2023. Sterling declined to celebrate.
Today's Key Points
  • Versus Friday: GBP/EUR is virtually unchanged; GBP/USD has slipped about 37 pips from 1.3395 to 1.3358.
  • August public-sector borrowing printed £18.3bn — above the £15.7bn consensus and £3.5bn above the OBR forecast.
  • An hour later the CBI order-book balance jumped to −9 from −25, against a forecast of −34. Strongest since July 2023.
  • Sterling treated the good factory news with the enthusiasm of a man offered a second cup of lukewarm tea.
  • Mood is orderly, not excited. Last week’s G3 rate decisions are still being digested; ranges have narrowed.
  • Today’s remaining items: Richmond Fed (14:00 UK) and euro-area flash consumer confidence. The week’s real test is tomorrow’s flash PMIs.
  • Current mid-market ranges: GBP/EUR €1.1578–€1.1660 | GBP/USD $1.3256–$1.3356.
  • For euro property buyers the rate has not rewarded waiting since Friday. Timing and clean execution remain the larger part of the sum.
  • New in this report: Property Buyer Spotlight – see the real 1-week, 1-month and 3-month high/low ranges and what they mean for a £250,000 transfer.
Market Overview

Friday 18 September left a reasonably tidy close: GBP/EUR at 1.1662, GBP/USD at 1.3395 after a 1.3336–1.3398 dollar range. Four sessions on, the euro cross has barely left the room. The dollar cross has given Friday’s bounce back in an orderly fade, not a rout. That is the whole weekend in one sentence.

This morning then offered two contradictory UK prints and the market, being British about it, accepted both. Borrowing was heavier than hoped; factory orders were the best in three years. Neither moved GBP/EUR more than a few pips. The tape is waiting for Wednesday’s flash PMIs — the first activity read after last week’s BoE hold, Fed hike and BoJ rise. Quiet is not the same as cheap, and it is not the same as settled.

GBP/EUR Analysis

GBP/EUR: €1.1578–€1.1660 | Level: ~1.1658 (0.8578)

  • The CBI beat (−9 vs −34) would normally have asked a little more of this pair. It received a polite acknowledgement and nothing more.
  • The £18.3bn borrowing miss would normally have asked a little less. Same result.
  • Euro-area flash consumer confidence is still on the afternoon slate (forecast −16.0, prior −15.5). Wednesday’s PMI cluster is the larger risk to the range.
Educational note: A pair that absorbs a three-year high in factory orders and an oversized fiscal miss inside a 20-pip box is not “ignoring data”. It is ranking it. Last week’s policy decisions are already in the price; the next activity survey is not. That is why Wednesday 08:30 UK matters more for this cross than anything printed this morning. For a buyer converting a deposit, the Friday-to-Tuesday move is almost nothing — which is either welcome stability, or a warning not to wait for a prettier print that may never arrive.
PROPERTY BUYER SPOTLIGHT
Timing, Range & the Bigger Picture
 

This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.

Period High Low £250k at High £250k at Low Difference
1 Week 1.1693 1.1619 €292,325 €290,475 €1,850
1 Month 1.1703 1.1617 €292,575 €290,425 €2,150
3 Months 1.1809 1.1587 €295,225 €289,675 €5,550

The numbers show that movement is real, even when the market feels quiet. Most buyers naturally focus on the rate itself. Yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate achieved with poor support or unexpected delays can easily cost more than a well-timed transfer executed smoothly.

For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so that the money arrives exactly when it is needed, without stress?”

Want to see a different amount or timeline? try our useful calculator...
Try Calculator Here

GBP/USD Analysis

GBP/USD: $1.3256–$1.3356 | Current: ~1.3358 (0.7486)

  • Friday’s dollar-side bounce has been handed back. The Fed’s 25 bp rise to 3.75–4.00% last week is still the heavier hand on this pair.
  • The CBI surprise did not buy sterling a lasting bid against the dollar. Borrowing did not sell it hard either.
  • Richmond Fed (forecast 5, prior 4) was due at 14:00 UK as this note was compiled; Fed speakers follow. Friday’s durable-goods print is the week’s US headline.
Educational note: Since Friday the story has split by pair. GBP/EUR has stood still; GBP/USD has drifted. That is not a forecast and it is not a recommendation. It is a practical observation: the rate that matters is the one you actually settle, on the day the funds must clear. A 37-pip fade on a dollar invoice is visible. The same four days on a euro purchase are barely a rounding error. Timing, as ever, is doing more work than the headline rate.

EUR/USD Analysis

EUR/USD: ~1.1462 (0.8724)

  • That mild divergence is the cleanest read of the past four sessions: sterling holding its euro rate while both European currencies lean into a firmer dollar.
  • Flash euro-area consumer confidence is still due (forecast −16.0). German Ifo on Thursday is the next local test of morale.
  • Dollar tone after last week’s Fed hike remains the overlay. There has been no euro-specific shock today.
Educational note: Three pairs, one geometry. If GBP/EUR is flat and EUR/USD is softer, sterling is quietly outperforming the euro even as both give ground to the dollar. Wednesday’s PMI set will either confirm that split or flatten it. No call either way — only the shape of the tape since Friday’s report.

Weekly Economic Calendar

Date Time (UK) Currency Event Actual / Forecast Previous Imp.
Tue 22 Sep (Today) 06:00 GBP Public Sector Net Borrowing (Aug) £18.3bn / £15.7bn £2.0bn* ★★
Tue 22 Sep (Today) 11:00 GBP CBI Industrial Trends Orders (Sep) −9 / −34 −25 ★★
Tue 22 Sep (Today) 14:00 USD Richmond Fed Mfg Index (Sep) due / 5 4 ★★
Tue 22 Sep (Today) 15:00 EUR Consumer Confidence flash (Sep) – / −16.0 −15.5 ★★
Wed 23 Sep 08:30 GBP S&P Global Flash PMIs (Sep) – / Mfg 51.4 / Svc 52.0 52.5 / 52.5 ★★★
Wed 23 Sep 08:15–09:00 EUR Flash PMIs — EZ / DE / FR (Sep) – / cluster ★★★
Thu 24 Sep 09:00 EUR Germany Ifo Business Climate (Sep) – / 87.0 88.8 ★★★
Thu 24 Sep 13:30 / 15:00 USD US Current Account (Q2) / New Home Sales (Aug) ★★
Fri 25 Sep 13:30 / 15:00 USD Durable Goods (Aug P) / UoM Sentiment (Sep F) ★★★


Conclusion

Since Friday the euro cross has sat still, the dollar cross has slipped a little, and Britain has published both a chunky borrowing miss and its best factory-order reading since 2023. Only a very British tape could greet that pairing with a shrug and a 20-pip range. Tomorrow’s flash PMIs will decide whether the shrug was wisdom or merely good manners. For property buyers and businesses the practical point is unchanged: GBP/EUR has not rewarded waiting since Friday, and a transfer that arrives on time still tends to beat a slightly prettier rate that does not. The dome is still standing. So is the pair.

This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.