|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
October 21st 2026 |
|
| NEW |
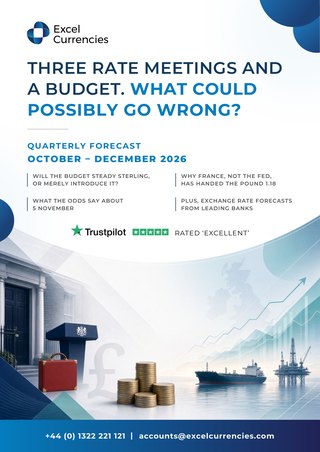
Quarterly Forecast · Q4 2026 |
|
|
| Three rate meetings and a Budget. What could possibly go wrong? |
| October – December 2026 |
| ✓ |
Will the Budget steady sterling, or merely introduce it? |
| ✓ |
Why France, not the Fed, handed the pound 1.18 |
| ✓ |
What the odds say about 5 November |
| ✓ |
Exchange rate forecasts from leading banks |
|
|
|
| Where banks see rates by January 2027 |
GBP/EUR
1.12 – 1.19
€70,000 gap on £1m
|
|
GBP/USD
1.28 – 1.35
$70,000 gap on £1m
|
|
EUR/USD
1.13 – 1.16
$30,000 gap on €1m
|
|
| Four dates that could move your rate |
28 OCT
UK Budget
|
28 OCT
Federal Reserve decision
|
29 OCT
ECB decision
|
5 NOV
Bank of England decision
|
|
|
|
| Free PDF · 11 pages · Bank forecasts, key-event calendar & economic outlook |
| Ranges are the spread of published bank and consensus forecasts, Bloomberg, 5 October 2026. Not dealing rates and not an Excel Currencies forecast. |
|
|
| Sterling Holds Above 1.19 as UK Data Supports the Pound |
Today's Key Points
- Sterling has pushed firmly into the 1.19+ zone against the euro since Monday’s report, helped by stronger UK jobs data and today’s hotter inflation print.
- UK CPI hit 3.5% (above the 3.4% forecast), reinforcing expectations of a Bank of England rate rise in November and keeping the pound supported.
- Many bank forecasts still see GBP/EUR drifting back toward 1.15 by year-end, so the current 1.19+ level stands out as a relatively attractive window versus those longer-term projections.
- For people buying property in Europe, this is a constructive backdrop: more euros per pound than the consensus outlook implies for later in the quarter.
- Markets remain focused on next week’s Budget and Friday’s retail sales plus flash PMIs; today’s move has been steady rather than explosive.
- Current mid-market ranges: GBP/EUR €1.1810–€1.1928 | GBP/USD $1.3267–$1.3376. Spot: GBP/EUR 1.1928 (0.8383), GBP/USD 1.3397, EUR/USD 1.1234.
Market Overview
Since Monday morning the pound has been the clearer winner in the majors. Tuesday’s labour-market numbers showed unemployment falling to 4.7% (better than the 4.9% expected), and this morning’s CPI confirmed the price picture is still sticky. Inflation rose to 3.5% year-on-year in September, the highest in nearly a year, with motor fuels doing most of the heavy lifting. Public borrowing for the month also came in above forecast at £24.5 billion, a timely reminder that the Budget on 28 October will be watched closely. Sterling has held and extended gains, trading solidly above 1.19 versus the euro and near one-month highs against the dollar. The broader mood is one of cautious support for the pound rather than euphoria; higher rates are being priced in, but the fiscal backdrop and Friday’s activity data will decide whether the move has more room or simply consolidates. French political noise remains a soft headwind for the euro, which has helped the relative sterling story.
GBP/EUR Analysis
GBP/EUR: €1.1810–€1.1928 | Level: ~1.1928 (0.8383)
- Over the past 24 hours the pair has ranged by roughly 0.35% (high near 1.1930, low near 1.189), with a net gain of about 0.15% as the pound extended its post-data strength.
- The pair has spent the past two days grinding higher after Monday’s close, clearing and holding the 1.19 handle that featured in the latest quarterly forecast.
- Stronger UK data has widened the perceived interest-rate gap with the euro area, and several banks (including an upgraded ING view and longer-standing targets from Bank of America and UBS around 1.19) are now more comfortable with sterling than they were a few weeks ago.
- Consensus forecasts still cluster nearer 1.15 by the end of the year, which makes the present level stand out as a useful reference point rather than a permanent plateau.
- Friday’s UK and euro-area flash PMIs will be the next test of whether demand is matching the price data; any softer reading could invite a pause.
Educational note: When spot sits above most published year-end forecasts, it does not automatically mean the rate must reverse tomorrow. It does, however, illustrate that the market is currently pricing a more favourable near-term path for the pound than the average bank projection. For property buyers, that gap is worth noting while it lasts—more euros for each pound transferred today than the median outlook implies for December.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.1929 |
1.1860 |
€298,225 |
€296,500 |
€1,725 |
| 1 Month |
1.1929 |
1.1620 |
€298,225 |
€290,500 |
€7,725 |
| 3 Months |
1.1929 |
1.1600 |
€298,225 |
€290,000 |
€8,225 |
The numbers show that movement is real, even when the market feels quiet. Most buyers naturally focus on the rate itself. Yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate achieved with poor support or unexpected delays can easily cost more than a well-timed transfer executed smoothly.
For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so that the money arrives exactly when it is needed, without stress?” With the pound trading above 1.19 and many bank forecasts looking lower later in the year, the current window is one of the more constructive environments property buyers have seen for a while.
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: $1.3267–$1.3376 | Current: ~1.3397
- The pair has moved within a 24-hour range of approximately 0.4% (high near 1.341, low near 1.334), with a net gain of roughly 0.2%.
- Sterling has extended its recent climb against the dollar, supported by the same UK data that lifted it versus the euro. The pair is now testing the upper end of its one-month range.
- US data this week is secondary (jobless claims tomorrow, flash PMIs on Friday), so the domestic UK story and the approach of the Budget remain the dominant influences.
- The dollar has not collapsed; it has simply failed to reclaim ground while UK rate expectations have firmed. The move has been orderly rather than dramatic—more of a steady push than a sprint.
Educational note: A currency can strengthen on relative rate expectations even when absolute levels of inflation are still elevated. The practical implication for the rest of the week is that any US data surprise strong enough to revive dollar demand could cap further gains, while confirmation of UK resilience would leave the path of least resistance higher. Either way, the pair is responding more to the UK side of the equation at present.
EUR/USD Analysis
EUR/USD: ~1.1234
- Over the past 24 hours the pair has ranged by about 0.25% (high near 1.126, low near 1.121), with a modest net gain.
- The euro has recovered some ground against the dollar over the past day or so, but it has lagged the pound. The contrast is visible in the cross: sterling has benefited more from the UK inflation and jobs prints.
- The euro continues to carry residual caution around French fiscal and political developments.
- Friday’s coordinated flash PMIs will be the cleanest test of whether euro-area activity is stabilising or still lagging. Until then the single currency is moving more with broader dollar swings than with any fresh domestic catalyst.
Educational note: Divergence between two currencies that share a common counterpart (the dollar) often shows up first in the cross rate. Here the pound has outpaced the euro, reflecting the differing near-term policy trajectories. The week ahead’s PMI releases should clarify whether that gap narrows or persists into next week’s central-bank and budget events.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Tue 20 Oct |
07:00 |
GBP |
Unemployment Rate |
4.7% / 4.9% |
4.9% |
★★ |
| Wed 21 Oct (Today) |
07:00 |
GBP |
CPI y/y (Sep) |
3.5% / 3.4% |
3.1% |
★★★ |
| Thu 22 Oct |
13:30 |
USD |
Initial Jobless Claims |
– / 200K |
199K |
★★ |
| Fri 23 Oct |
07:00 |
GBP |
Retail Sales m/m |
– / -0.1% |
0.5% |
★★★ |
| Fri 23 Oct |
09:00 |
EUR |
Flash Manufacturing PMI |
– |
52.7 |
★★ |
| Fri 23 Oct |
09:30 |
GBP |
Flash Manufacturing PMI |
– |
51.9 |
★★ |
| Fri 23 Oct |
14:45 |
USD |
Flash Manufacturing PMI |
– / 55.5 |
55.9 |
★★ |
Conclusion
Sterling has used the stronger jobs and inflation data to push GBP/EUR comfortably into the 1.19+ area that featured in the quarterly outlook, a level that looks relatively favourable compared with many bank forecasts pointing lower by year-end. For property buyers that is a constructive development: the current rate delivers more euros than the consensus path implies later in the quarter. The rest of the week is quieter until Friday’s retail sales and PMI cluster, which should show whether demand is keeping pace with prices. Overall the tone is one of steady support for the pound rather than unbridled enthusiasm—useful while it lasts, and worth watching closely around next week’s Budget.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin