Today's Key Points
- Sterling held relatively firm against the euro while softening against the dollar as markets digested mixed UK labour data and a modest CPI uptick.
- UK unemployment edged down to 4.6% on Tuesday, with slower wage growth leaving Bank of England hike expectations largely intact.
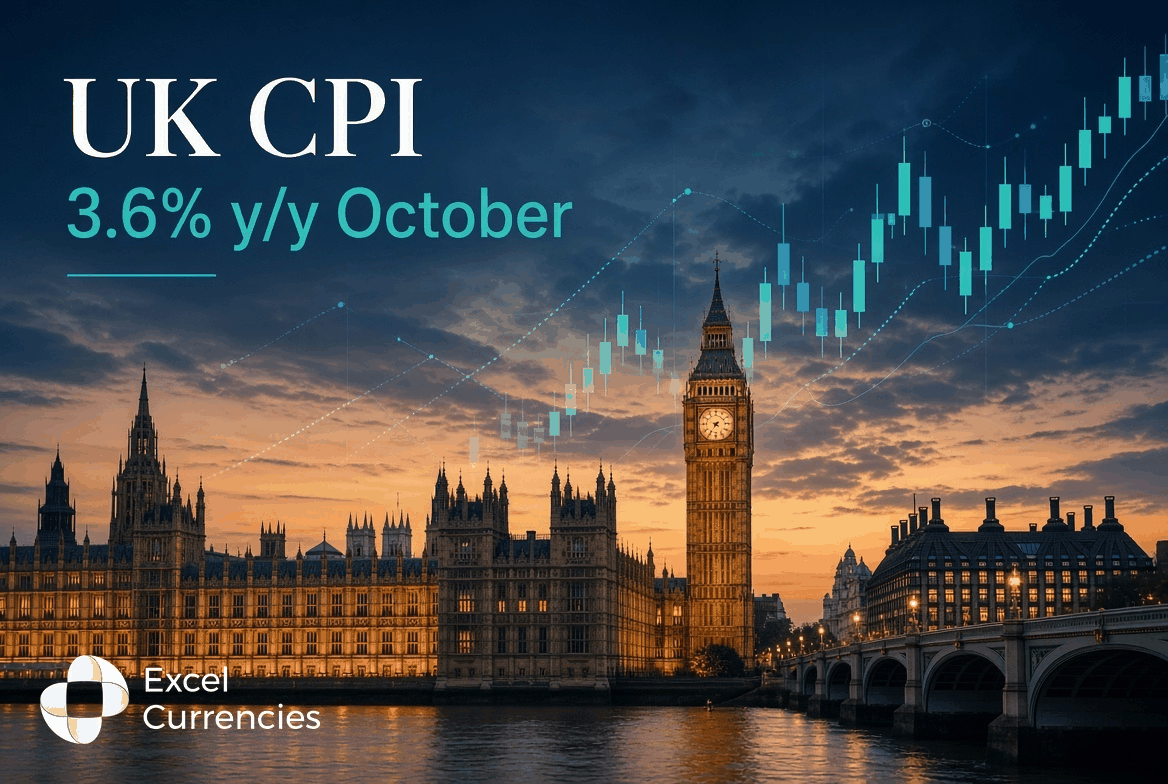
- October UK CPI rose to 3.6% year-on-year (from 3.5%), slightly softer than some forecasts, while core stayed at 2.8%.
- US retail sales grew a moderate 0.2% in October, supporting the dollar alongside hawkish Federal Reserve commentary.
- Market mood remains cautious ahead of tonight’s FOMC minutes, with tech and risk sentiment still influential after Nvidia’s results.
- Today’s main focus was the UK inflation print; the rest of the week brings US jobless claims, UK retail sales and further central-bank colour.
- Forward view: no rate decisions this week, but data and minutes will shape December pricing for both the BoE and Fed.
- Even a contained range still moves the numbers over time: see the table showing the euro difference on a £250,000 transfer – up to €9,975 between the three-month low and the recent high.
- With the FOMC minutes tonight and UK retail sales on Friday, know where the banks see sterling heading: download our free Q4 Quarterly Forecast for rate forecasts, the key-event calendar and what this week’s data could mean for your transfer.
Market Overview
The past 24 hours saw sterling navigate a mixed set of UK releases while the dollar drew support from resilient US consumption data and ongoing hawkish Fed rhetoric. Tuesday’s labour-market figures showed unemployment falling to 4.6% against a 4.7% forecast, though wage growth slowed, leaving markets still pricing a high probability of a further Bank of England increase in December after the earlier move to 4%. Today’s CPI print confirmed inflation edged up to 3.6%, driven mainly by transport costs, yet remained a touch below some expectations and left core unchanged. US retail sales matched forecasts at +0.2%, reinforcing the sense of steady, if not spectacular, demand.
Risk sentiment stayed subdued after Tuesday’s sharp FTSE decline on Nvidia-related caution. Looking ahead, the FOMC minutes this evening and Thursday’s US claims will provide the next colour, followed by Friday’s UK retail sales and borrowing numbers. No major rate decisions fall this week, so the focus remains on how the data recalibrates December expectations. In practice, the difference between a well-timed transfer and one that sits in process for an extra day or two often outweighs the modest rate movement itself, particularly when documentation and settlement windows are tight.
GBP/EUR Analysis
GBP/EUR: relatively contained, firming slightly after the labour data and holding ground after CPI
Sterling has traded in a relatively contained range against the euro over the last 24–48 hours, firming slightly after the labour data and holding ground following the CPI release. The pair has been supported by the BoE’s recent hike and still-elevated hike pricing, while eurozone inflation remains elevated but without fresh policy surprises.
- UK unemployment fell to 4.6% (forecast 4.7%), with employment rising and inactivity edging lower, though slower pay growth tempered the hawkish impulse.
- October CPI at 3.6% y/y (prior 3.5%) was a touch softer than some consensus views; core held at 2.8%.
- Eurozone final inflation figures around 4.0% provided little fresh divergence.
- Broader risk aversion after Tuesday’s equity weakness limited upside for sterling crosses.
Educational note: Even when headline rates look quiet, the interaction between labour-market tightness and inflation persistence can shift the relative path of interest rates between the UK and eurozone over the coming weeks. A small change in the expected timing of the next BoE or ECB move can alter the carry available on the pair more than the daily range itself. For anyone moving larger sums, the practical question is often whether the process (confirmation of funds, cut-off times, and beneficiary details) can be completed cleanly inside the window when the rate is favourable, rather than whether the rate has ticked another 20 pips.
|

 X
 Facebook
 linkedin