|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
September 17th 2026 |
|
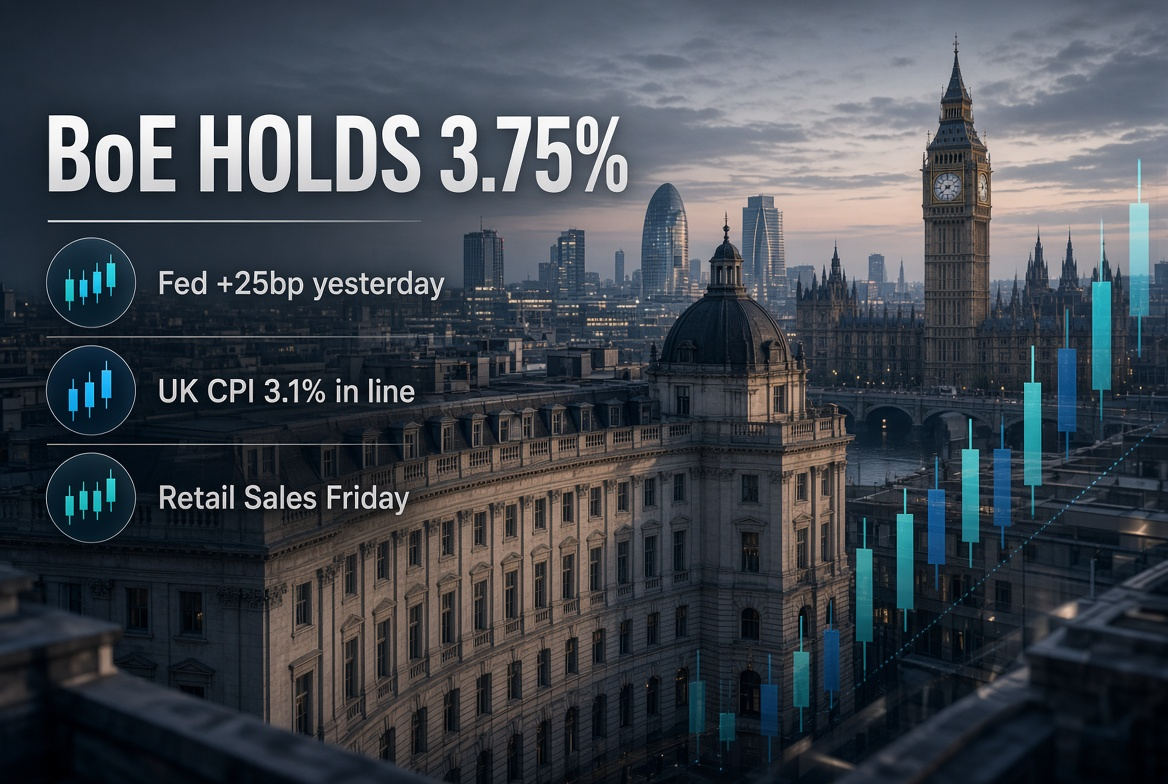
| BoE holds 3.75% after Fed’s first hike since 2023 |
Today's Key Points
- The Bank of England has just held Bank Rate at 3.75%, matching the widely expected outcome.
- That follows yesterday’s Federal Reserve hike of 25bp to 3.75–4.00% — the Fed’s first increase since 2023.
- Since Tuesday, sterling’s main move has been against the dollar, not the euro: GBP/USD fell after CPI and the Fed, then steadied into today’s hold.
- UK CPI printed 3.1% yesterday, exactly as forecast; core stayed at 2.6%.
- Immediate market reaction to the hold has been orderly rather than dramatic; attention now turns to the minutes, any QT update and this afternoon’s US data.
- Friday’s UK retail sales close the week.
- Current mid-market ranges: GBP/EUR €1.1550–€1.1667 | GBP/USD $1.3310–$1.3410.
- New in this report: Property Buyer Spotlight – see the real 1-week, 1-month and 3-month high/low ranges and what they mean for a £250,000 transfer.
Market Overview
Two central banks have now spoken in 24 hours, and they did not move together. Yesterday the Fed raised rates by a quarter point to 3.75–4.00%, a unanimous vote and the first hike since July 2023. The dollar firmed and GBP/USD dropped from the mid-1.34s into the 1.337 area. This morning the Bank of England kept Bank Rate at 3.75%. That was the outcome markets had priced as the base case after Wednesday’s in-line 3.1% CPI print. Sterling has recovered a little against the dollar into the announcement, while GBP/EUR has stayed in a tight range. Prime Minister Andy Burnham’s comments yesterday about “difficult decisions” ahead of the Budget remain the main political backdrop, but today’s price action is about policy, not politics. US jobless claims and housing data are due at 13:30 UK; UK retail sales follow on Friday.
GBP/EUR Analysis
GBP/EUR: €1.1550–€1.1667 | Level: ~1.1674 (0.8566)
- The BoE hold did not jolt the cross; the pair has traded a few pips either side of 1.167 all morning.
- Yesterday’s UK CPI rise to 3.1% was fuel-heavy and left core unchanged at 2.6%, so it did not reprice sterling versus the euro.
- The euro’s own final August CPI confirmation this morning was also a non-event for the cross.
- Any lasting GBP/EUR move now depends less on the rate number and more on the minutes, the vote split and whether gilt-sale plans (QT) are slowed from the current £70bn annual pace.
Educational note: A “hold versus hike” week often looks louder on GBP/USD than on GBP/EUR. The Fed changed policy; the BoE did not. The cross therefore stays a language market: if the MPC sounds more worried about winter energy inflation than the ECB has recently, sterling can still firm against the euro without anyone changing Bank Rate today. That is the rest-of-week test, not a fresh rate surprise.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.1693 |
1.1629 |
€292,325 |
€290,725 |
€1,600 |
| 1 Month |
1.1700 |
1.1618 |
€292,500 |
€290,450 |
€2,050 |
| 3 Months |
1.1827 |
1.1519 |
€295,675 |
€287,975 |
€7,700 |
The numbers show that movement is real, even when the market feels quiet. Most buyers naturally focus on the rate itself. Yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate achieved with poor support or unexpected delays can easily cost more than a well-timed transfer executed smoothly.
For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so that the money arrives exactly when it is needed, without stress?”
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: $1.3310–$1.3410 | Current: ~1.3402
- Tuesday’s starting point was a relatively calm mid-1.34s tape.
- Wednesday’s sequence did the damage: UK CPI in line at 3.1%, then the Fed’s 25bp hike. Cable fell through the session to the 1.337 area.
- Overnight it found a floor near 1.3369. This morning’s recovery to 1.3402 came into the BoE hold, not as a shock after it.
- The hold removes the small chance of a same-day UK hike sitting on top of yesterday’s US hike. That is why the immediate reaction has been a grind higher rather than a spike.
- 13:30 UK brings US claims, housing starts and the Philadelphia Fed index — the next dollar test.
Educational note: When the Fed hikes and the BoE holds, sterling usually gives ground first and then asks a second question: was the UK hold dovish or merely patient? Since Tuesday the first leg has already happened. The second leg, if there is one, will come from the wording around second-round energy effects and from Friday’s retail sales, not from the 3.75% headline itself.
EUR/USD Analysis
EUR/USD: ~1.1477
- The euro took the same dollar punch as sterling after yesterday’s Fed decision.
- Final eurozone CPI this morning did not change the picture.
- Divergence versus sterling remains modest: both European currencies lost ground to the dollar together after the hike, and both have only partially retraced.
- Afternoon US data and Friday’s Bank of Japan decision keep the dollar in charge into the weekend.
Educational note: A Fed hike with the BoE and ECB on hold often keeps EUR/USD and GBP/USD moving in step for a day or two. The week-ahead split, if it appears, will be sterling-specific: a hawkish-sounding BoE hold can lift GBP/USD more than EUR/USD even while both stay below Tuesday’s levels.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Mon 15 Sep |
07:00 |
GBP |
Unemployment Rate (3m to Jul) |
4.9% / 5.0% |
4.9% |
★★ |
| Wed 16 Sep |
07:00 |
GBP |
CPI YoY (Aug) |
3.1% / 3.1% |
2.9% |
★★★ |
| Wed 16 Sep |
07:00 |
GBP |
Core CPI YoY (Aug) |
2.6% / 2.6% |
2.6% |
★★★ |
| Wed 16 Sep |
19:00 |
USD |
Fed Funds Rate Decision |
3.75–4.00% |
3.50–3.75% |
★★★ |
| Thu 17 Sep (Today) |
12:00 |
GBP |
BoE Interest Rate Decision |
3.75% hold / 3.75% |
3.75% |
★★★ |
| Thu 17 Sep (Today) |
12:00 |
GBP |
MPC Minutes / QT annual review |
Just released |
£70bn prior year |
★★★ |
| Thu 17 Sep (Today) |
13:30 |
USD |
Initial Jobless Claims |
– / 207k |
206k |
★★★ |
| Thu 17 Sep (Today) |
13:30 |
USD |
Housing Starts / Building Permits |
– / 1.32M / 1.40M |
1.24M / 1.43M |
★★ |
| Fri 18 Sep |
07:00 |
GBP |
Retail Sales MoM / YoY (Aug) |
– / −0.2% / 1.9% |
−0.5% / 1.6% |
★★★ |
| Fri 18 Sep |
Early |
JPY |
BoJ Interest Rate Decision |
– / 1.25% |
1.00% |
★★★ |
Conclusion
Since Tuesday the tape has had a simple shape: UK inflation did what it was supposed to do, the Fed hiked, the dollar took the first prize, and the Bank of England has now chosen patience at 3.75%. Sterling’s bruise is against the greenback; against the euro it has barely left the room. The rest of Thursday is about the small print — minutes, any slowing of gilt sales, then US claims. Friday’s retail sales will show whether households are already tightening after dearer fuel. No forecasts here, just the sequence: hike in Washington yesterday, hold in London today, data tomorrow.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin