|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
September 15th 2026 |
|
| UK Jobs Mixed, Pay Cools to 3.9% — CPI, FOMC and BoE Still Ahead |
Today's Key Points
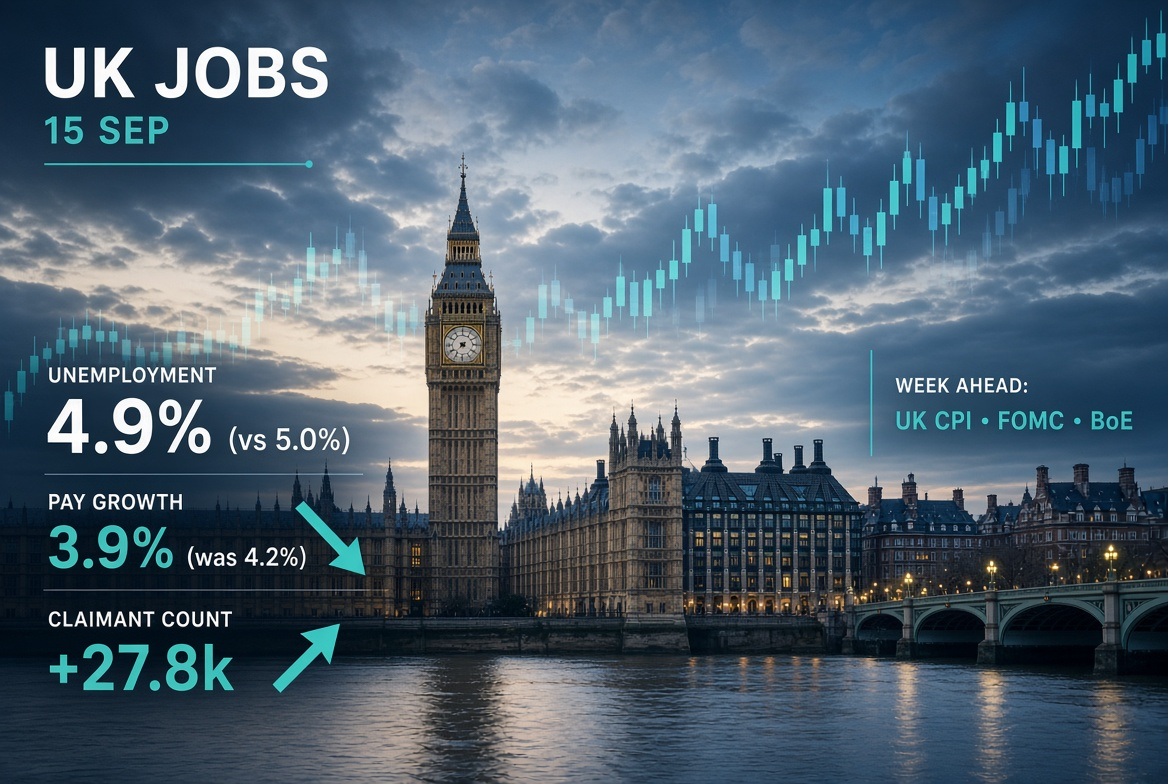
- UK jobs landed mixed at 7:00 AM: unemployment stayed at 4.9% (expected 5.0%), pay growth slowed to 3.9%, but claimant count jumped by 27,800.
- From Friday’s close the pound is a little softer against the dollar and a little firmer against the euro.
- French and Spanish inflation reprints confirmed firmer euro-area prices; German wholesale prices also ran hot.
- Market mood is cautious ahead of UK CPI tomorrow, the Federal Reserve tomorrow evening and the Bank of England on Thursday.
- Current mid-market ranges: GBP/EUR €1.1555–€1.1659 | GBP/USD $1.3356–$1.3478.
- New in this report: Property Buyer Spotlight – see the real 1-week, 1-month and 3-month high/low ranges and what they mean for a £250,000 transfer.
- Away from the screens: Liverpool and Scotland legend Graeme Souness starts a three-day climb-and-swim today for Debra UK, aiming to raise at least £500,000 for families living with “butterfly skin”. www.debra.org.uk
Market Overview
The stretch from Friday has been a dollar story first and a UK-data story this morning. Oil-led safe-haven demand on Monday pushed sterling to a one-month low against the greenback, even as the pound gained a little on the euro. The ONS labour report then reset the domestic picture without settling it. Headline unemployment held at 4.9% rather than rising to 5.0%, and regular pay excluding bonuses stayed at 3.5%. Total pay including bonuses cooled to 3.9% from 4.2%. The sting was the claimant count, which rose 27,800 against an 8,300 expectation. That mix still leaves Thursday’s Bank of England meeting framed as a likely hold at 3.75%, but it does not close the argument. Euro-area inflation finals from France and Spain, plus a sharp German wholesale-price print, keep imported-price pressure on the table. Ahead sit Wednesday’s UK CPI and US retail sales, the FOMC decision later that evening, the MPC announcement on Thursday and Friday’s UK retail sales. Energy prices and those two central-bank decisions are what the crosses are pricing this week.
GBP/EUR Analysis
GBP/EUR: €1.1555–€1.1659 | Level: ~1.1682 (0.8560)
- Sterling recovered on the euro through Monday as the single currency absorbed more of the dollar’s bid.
- This morning’s jobs mix did not break that range: cooler pay growth limited any hawkish impulse, while the claimant-count spike capped any dip-buying.
- French CPI confirmed at 2.4% year-on-year and Spanish HICP printed 4.6%, so euro-area inflation is not fading in lockstep with UK pay.
- German ZEW at 10:00 UK and Wednesday’s UK CPI are the next two tests of whether 1.17 remains a ceiling or a floor.
The pair has spent the period since Friday climbing out of the mid-1.16s toward 1.17 as last week’s UK growth surprise lingered and the euro paid a larger share of the oil shock. That leaves a narrow, two-sided tape into the Bank of England. A hotter CPI print tomorrow would argue for more euro weakness against sterling; a cooler print, or a dovish-looking MPC vote split on Thursday, would give the euro a chance to reclaim Friday’s lows. Neither outcome is priced as a one-way bet.
Educational note: Labour-market releases often pull a currency in two directions at once. Unemployment and claimant-count figures speak to spare capacity; pay growth speaks to the cost of that capacity. When the two disagree — as they did this morning — the next inflation print usually decides which story the market keeps. That is why Wednesday’s CPI carries more weight for GBP/EUR this week than today’s jobs headline on its own.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.1693 |
1.1625 |
€292,325 |
€290,625 |
€1,700 |
| 1 Month |
1.1721 |
1.1616 |
€293,025 |
€290,400 |
€2,625 |
| 3 Months |
1.1828 |
1.1516 |
€295,700 |
€287,900 |
€7,800 |
The numbers show that movement is real, even when the market feels quiet. Most buyers naturally focus on the rate itself. Yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate achieved with poor support or unexpected delays can easily cost more than a well-timed transfer executed smoothly.
For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so that the money arrives exactly when it is needed, without stress?”
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: $1.3356–$1.3478 | Current: ~1.3477
- Monday’s slide was imported: oil firmer, the dollar bid, gilt yields still elevated — not a UK-specific sell-off.
- This morning’s 4.9% jobless rate stopped the pair from extending the early-London dip below 1.3470, but cooler pay growth offered the dollar a second look.
- US data still due today is the Empire State manufacturing index (forecast 15.0 after 20.6).
- Wednesday packs US retail sales (forecast +0.8% after −0.6%) and the FOMC statement into the same session as UK CPI.
Cable has spent the period since Friday slipping from the mid-1.35s toward last week’s floor after failing to hold 1.35 into the US session on Monday. The dollar’s advantage this week is institutional as much as cyclical: the Federal Reserve decides first, and any firming of the US funds rate would briefly put dollar overnight money above sterling’s 3.75% Bank Rate. That is a short-lived technical fact, not a verdict on the pound’s year. Thursday’s MPC vote, the accompanying statement and any change in the 6–3 July split will decide whether sterling can rebuild toward 1.35 or whether 1.3450 remains the working low into Friday’s retail-sales print.
Educational note: When oil jumps, the dollar often firms first because energy is priced in dollars and US yields tend to rise with inflation-risk premia. Sterling can look “weak” on the same day it is merely less used as a haven. Separating that dollar bid from a genuine UK-rate story is the whole point of this week’s sequence — jobs today, CPI tomorrow, Bank of England on Thursday.
EUR/USD Analysis
EUR/USD: ~1.1538
- The euro gave more ground to the dollar than sterling did, which is why GBP/EUR firmed even as cable fell.
- Final August CPI from France (2.4%) and Spain (HICP 4.6%) confirmed that euro-area prices are still uneven rather than uniformly cooling.
- German wholesale prices rose 0.9% on the month and 6.8% on the year — a pipeline reminder, not a consumer-price print.
- ZEW sentiment (Germany forecast 39.8 after 34.2; euro area 39.2 after 31.4) is today’s European event risk.
EUR/USD is the pair most tightly tied to Wednesday night. US retail sales at 13:30 UK and the FOMC decision later the same day sit on top of an already firmer dollar. The divergence with sterling is visible in the crosses: the pound has been the less-punished European currency since Friday, helped by still-restrictive UK policy and this morning’s unemployment hold. That ranking can reverse quickly if UK CPI undershoots and the Fed sounds firmer than the MPC. Until those two statements are out, 1.15 remains a magnet rather than a breakout level.
Educational note: Cross-rate math is not optional this week. If EUR/USD falls faster than GBP/USD, GBP/EUR rises even when both European currencies look heavy against the dollar. Watching only one pair can make a quiet sterling tape look stronger — or weaker — than the underlying dollar move.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Mon 14 Sep |
— |
USD / GBP |
Oil-led dollar bid; sterling one-month low vs USD |
– |
– |
★★ |
| Tue 15 Sep (Today) |
07:00 |
GBP |
Average Earnings +Bonus (Jul) |
3.9% / 3.9% |
4.2% |
★★ |
| Tue 15 Sep (Today) |
07:00 |
GBP |
Claimant Count Change (Aug) |
+27.8K / +8.3K |
−11.8K |
★★ |
| Tue 15 Sep (Today) |
07:00 |
GBP |
Unemployment Rate (Jul) |
4.9% / 5.0% |
4.9% |
★★ |
| Tue 15 Sep (Today) |
07:00 |
GBP |
Average Earnings ex Bonus (Jul) |
3.5% / 3.5% |
3.5% |
★ |
| Tue 15 Sep (Today) |
07:00 |
EUR |
German WPI (MoM / YoY, Aug) |
0.9% / 6.8% / 0.1% |
0.2% / 5.3% |
★ |
| Tue 15 Sep (Today) |
07:45 |
EUR |
French CPI (YoY, Aug final) |
2.4% / 2.4% |
2.1% |
★★ |
| Tue 15 Sep (Today) |
08:00 |
EUR |
Spanish HICP (YoY, Aug final) |
4.6% / 4.5% |
3.9% |
★★ |
| Tue 15 Sep (Today) |
10:00 |
EUR |
German / Eurozone ZEW Sentiment (Sep) |
– / 39.8 / 39.2 |
34.2 / 31.4 |
★★ |
| Tue 15 Sep (Today) |
13:30 |
USD |
NY Empire State Manufacturing (Sep) |
– / 15.0 |
20.6 |
★★ |
| Wed 16 Sep |
07:00 |
GBP |
UK CPI (YoY, Aug) |
– / 3.2% |
2.9% |
★★★ |
| Wed 16 Sep |
13:30 |
USD |
US Retail Sales (MoM, Aug) |
– / +0.8% |
−0.6% |
★★★ |
| Wed 16 Sep |
19:00 |
USD |
FOMC Rate Decision & Statement |
– |
3.50–3.75% |
★★★ |
| Thu 17 Sep |
12:00 |
GBP |
Bank of England Bank Rate |
– / 3.75% hold |
3.75% |
★★★ |
| Thu 17 Sep |
13:30 |
USD |
US Housing Starts (Aug) |
– / 1.30M |
1.239M |
★★ |
| Fri 18 Sep |
07:00 |
GBP |
UK Retail Sales (Aug) |
– |
– |
★★★ |
| Fri 18 Sep |
14:15 |
USD |
US Industrial Production (Aug) |
– / +0.3% |
+0.2% |
★★ |
Conclusion
Tuesday morning leaves sterling in a holding pattern rather than a new trend. Since Friday the pound has given a little ground to the dollar and taken a little from the euro. Jobs data removed the fear of a 5.0% unemployment print and confirmed that pay growth is slowing, yet the claimant-count jump keeps the labour market from looking tidy. The rest of the week will be decided by whether Wednesday’s CPI and the two policy statements agree with each other.
And while the policy calendar does its work, Graeme Souness — 73, a Liverpool and Scotland captain, and now president of Debra UK — sets off today on three peaks and three high-altitude swims in three days. The aim is £500,000 toward treatments for epidermolysis bullosa, the rare “butterfly skin” condition that makes everyday contact painful for children and adults. Markets will still be here on Thursday. Some challenges matter more than a pip.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin