|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
October 14th 2026 |
|
| NEW |
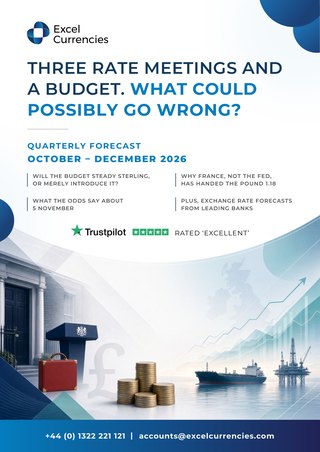
Quarterly Forecast · Q4 2026 |
|
|
| Three rate meetings and a Budget. What could possibly go wrong? |
| October – December 2026 |
| ✓ |
Will the Budget steady sterling, or merely introduce it? |
| ✓ |
Why France, not the Fed, handed the pound 1.18 |
| ✓ |
What the odds say about 5 November |
| ✓ |
Exchange rate forecasts from leading banks |
|
|
|
| Where banks see rates by January 2027 |
GBP/EUR
1.12 – 1.19
€70,000 gap on £1m
|
|
GBP/USD
1.28 – 1.35
$70,000 gap on £1m
|
|
EUR/USD
1.13 – 1.16
$30,000 gap on €1m
|
|
| Four dates that could move your rate |
28 OCT
UK Budget
|
28 OCT
Federal Reserve decision
|
29 OCT
ECB decision
|
5 NOV
Bank of England decision
|
|
|
|
| Free PDF · 11 pages · Bank forecasts, key-event calendar & economic outlook |
| Ranges are the spread of published bank and consensus forecasts, Bloomberg, 5 October 2026. Not dealing rates and not an Excel Currencies forecast. |
|
|
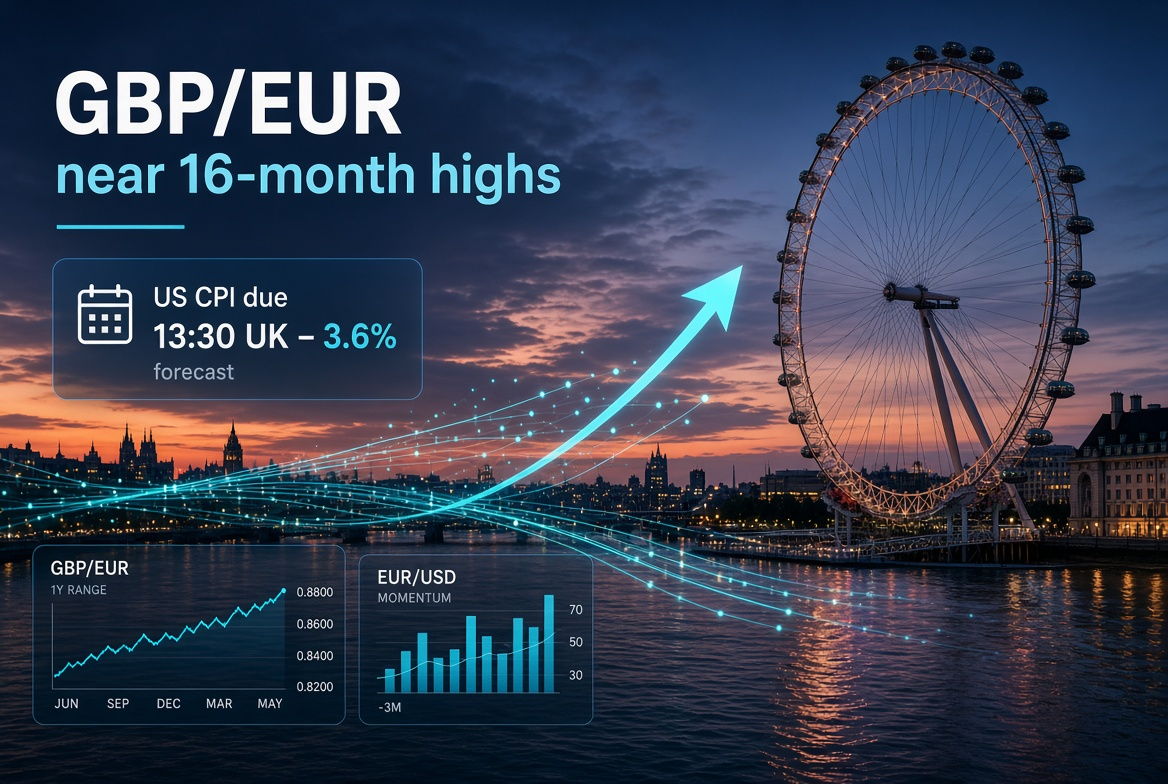
| Hotter US CPI Lifts Dollar – GBP/EUR Holds Near Multi-Month Highs |
Today's Key Points
- US inflation came in hotter than expected this afternoon, with headline CPI at 3.7% yearly and core at 2.6%.
- The dollar strengthened on the news, pushing sterling and the euro lower against it, though the pound held up better than the euro.
- GBP/EUR pushed higher to around 1.1864, remaining near its strongest levels in well over a year.
- Earlier comments from Bank of England’s Huw Pill expressing scepticism about four rate rises had supported the pound before the data.
- German wholesale prices were stronger than forecast earlier in the day, but the US figures dominated the reaction.
- The rest of the week still holds US retail sales and producer prices on Thursday, plus UK industrial and trade data.
- Current mid-market ranges: GBP/EUR €1.1761–€1.1857 | GBP/USD $1.3089–$1.3189. Spot: GBP/EUR 1.1864 (0.8429), GBP/USD 1.3207, EUR/USD 1.1139.
Market Overview
The past 24 hours were dominated by the US CPI release at 13:30 UK time. Headline consumer prices rose 0.6% on the month and 3.7% on the year (above the 3.6% forecast), while core inflation increased 0.3% monthly and 2.6% annually (both hotter than expected). Fuel costs were a major driver, and the firmer core reading revived expectations of a possible Federal Reserve rate increase later this month. The dollar strengthened in response, with the euro falling more sharply than sterling. Earlier in the day, Bank of England Chief Economist Huw Pill had said he was sceptical that markets are right to price four quarter-point BoE rises over the next year, which had given the pound a modest lift before the US data. German wholesale prices also came in stronger than expected. Looking ahead, Thursday brings US retail sales, producer prices and the Philadelphia Fed survey, alongside UK GDP, industrial production, manufacturing and trade balance figures for August, plus eurozone industrial production. Friday includes final eurozone CPI and trade data together with US industrial production and import prices. Ongoing IMF meetings continue to provide a backdrop of central-bank commentary.
GBP/EUR Analysis
GBP/EUR: €1.1761–€1.1857 | Level: ~1.1864 (0.8429)
- Over the past 24 hours the pair has ranged between roughly 1.1831 and 1.1864, a volatility of about 0.28%, with a net gain of around 0.23%..
- The hotter US CPI hit the euro harder than sterling, allowing the cross to push to fresh multi-month highs.
- Pill’s earlier scepticism on the scale of future BoE tightening had already helped the pound hold elevated levels against the euro.
- The pair remains close to its strongest levels in around 16–20 months, reflecting relative resilience in UK rate expectations.
Educational note: When US data drives a broad dollar move, the euro and pound can react differently if European or UK-specific factors are in play. Over the rest of the week, Thursday’s UK industrial and trade figures versus eurozone production data could influence whether the current elevated GBP/EUR levels hold or ease. For those managing larger transfers, periods when the rate sits near multi-month highs can sometimes allow greater certainty on both rate and timing through structured arrangements before subsequent releases shift the balance.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.1864 |
1.1755 |
€296,600 |
€293,875 |
€2,725 |
| 1 Month |
1.1864 |
1.1611 |
€296,600 |
€290,275 |
€6,325 |
| 3 Months |
1.1864 |
1.1603 |
€296,600 |
€290,075 |
€6,525 |
The numbers show that movement is real, even when the market feels quiet. Most buyers naturally focus on the rate itself. Yet the rate is only one part of the equation. What often makes the larger difference is the quality of guidance around when to transfer, how the process is managed, the clarity of communication, and the reliability of the people handling the money. A slightly better rate achieved with poor support or unexpected delays can easily cost more than a well-timed transfer executed smoothly. For property buyers currently able to secure euros at levels not seen for the better part of 20 months, the practical question is often how to lock in certainty of both rate and completion timing while the window remains open.
For early-stage buyers the real question is rarely just “what is the rate today?” It is “who will help me navigate the timing, the paperwork and the practicalities so that the money arrives exactly when it is needed, without stress?”
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: $1.3089–$1.3189 | Current: ~1.3207
- The pair has moved within a 24-hour range of roughly 1.3200–1.3276 (approximately 0.58%), recording a net decline of around 0.36% after the data.
- The hotter-than-expected US core CPI strengthened the dollar and reversed earlier sterling gains against it.
- Pill’s comments had helped the pound earlier, but the US inflation surprise dominated the afternoon move.
- Higher energy-related inflation risks remain in the background for both the UK and US.
Educational note: US inflation data usually sets the short-term direction for GBP/USD because of the dollar’s sensitivity to Federal Reserve expectations. A hotter core print typically lifts the dollar quickly, as seen today. Over the remainder of the week, Thursday’s US retail sales and producer prices will test whether the post-CPI dollar strength has further room to run or begins to fade, which will in turn influence how elevated sterling levels against the euro translate into the dollar pair.
EUR/USD Analysis
EUR/USD: ~1.1139
- The pair has seen a 24-hour range of roughly 1.1132–1.1212 (about 0.72%), with a net decline of around 0.53%..
- The hotter US core CPI pressured the euro more sharply than sterling, widening the gap in the crosses.
- Stronger German wholesale prices earlier offered only limited support before the US data.
- Ongoing French fiscal concerns and energy-price pressures continue to weigh on the single currency relative to the pound.
Educational note: When US data is the main driver, both EUR/USD and GBP/USD tend to move in the same direction, but the magnitude can differ if regional factors are present. Today’s firmer core inflation hit the euro harder, helping GBP/EUR extend its gains. Thursday’s eurozone industrial production figures, set against the US retail sales and PPI releases, will show whether this relative underperformance of the euro continues into the end of the week.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Wed 14 Oct (Today) |
01:00 |
EUR |
German WPI m/m |
1.9% / 0.6% |
0.9% |
★★ |
| Wed 14 Oct (Today) |
various |
GBP |
BoE Pill / Bailey speeches |
– |
– |
★★ |
| Wed 14 Oct (Today) |
13:30 |
USD |
CPI m/m & y/y (Sep) |
0.6% / 3.7% / 0.6% / 3.6% |
0.4% / 3.4% |
★★★ |
| Wed 14 Oct (Today) |
13:30 |
USD |
Core CPI m/m & y/y |
0.3% / 2.6% / 0.2% / 2.5% |
0.3% / 2.4% |
★★★ |
| Wed 14 Oct (Today) |
19:00 |
USD |
Fed Beige Book |
– |
– |
★★ |
| Thu 15 Oct |
07:00 |
GBP |
GDP, Industrial Production, Trade Balance (Aug) |
– / –0.1% / –0.1% / –21.8B |
0.4% / 0.2% / –21.0B |
★★★ |
| Thu 15 Oct |
10:00 |
EUR |
Industrial Production (Aug) |
– / 0.0% |
–0.1% |
★★ |
| Thu 15 Oct |
13:30 |
USD |
Retail Sales, PPI, Philly Fed (Sep/Oct) |
– / 0.3% / 0.5% / 27 |
1.2% / 0.4% / 37.8 |
★★★ |
| Fri 16 Oct |
10:00 |
EUR |
CPI Final (Sep), Trade Balance (Aug) |
– |
– |
★★ |
| Fri 16 Oct |
13:30–14:15 |
USD |
Import Prices, Industrial Production (Sep) |
– / 0.7% / 0.4% |
0.7% / 0.0% |
★★ |
Conclusion
The afternoon’s hotter-than-expected US inflation data has shifted the tone, strengthening the dollar and pushing both sterling and the euro lower against it, with the euro underperforming. This has allowed GBP/EUR to extend gains near its highest levels in many months. With UK industrial and trade figures, US retail sales and producer prices still ahead, the rest of the week is likely to remain data-driven. Current elevated levels against the euro continue to stand out relative to the past year and more as further releases arrive.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin