|
|
| Daily Market Report |
Currency insight from
Excel Currencies |
|
|
|
|
Written by Karl Daly
Thursday 1 October 2026 |
|
| House prices cool to 0.8% — sterling minds the Budget, not the Etihad |
Today's Key Points
- Since 24 September, sterling is softer against the dollar. GBP/USD is around 1.3228, down roughly 2% on the month. GBP/EUR is steadier, near 1.1705 (0.8544). EUR/USD is near 1.1290.
- Labour conference: John Healey restated the fiscal rules and avoided the word tax. Andy Burnham said the triple lock would change from 2030. A wealth-tax motion passed. It is not a Budget. That is still 28 October.
- Elsewhere, an independent commission found Manchester City guilty on the major financial charges. The club will appeal. Sterling did not notice.
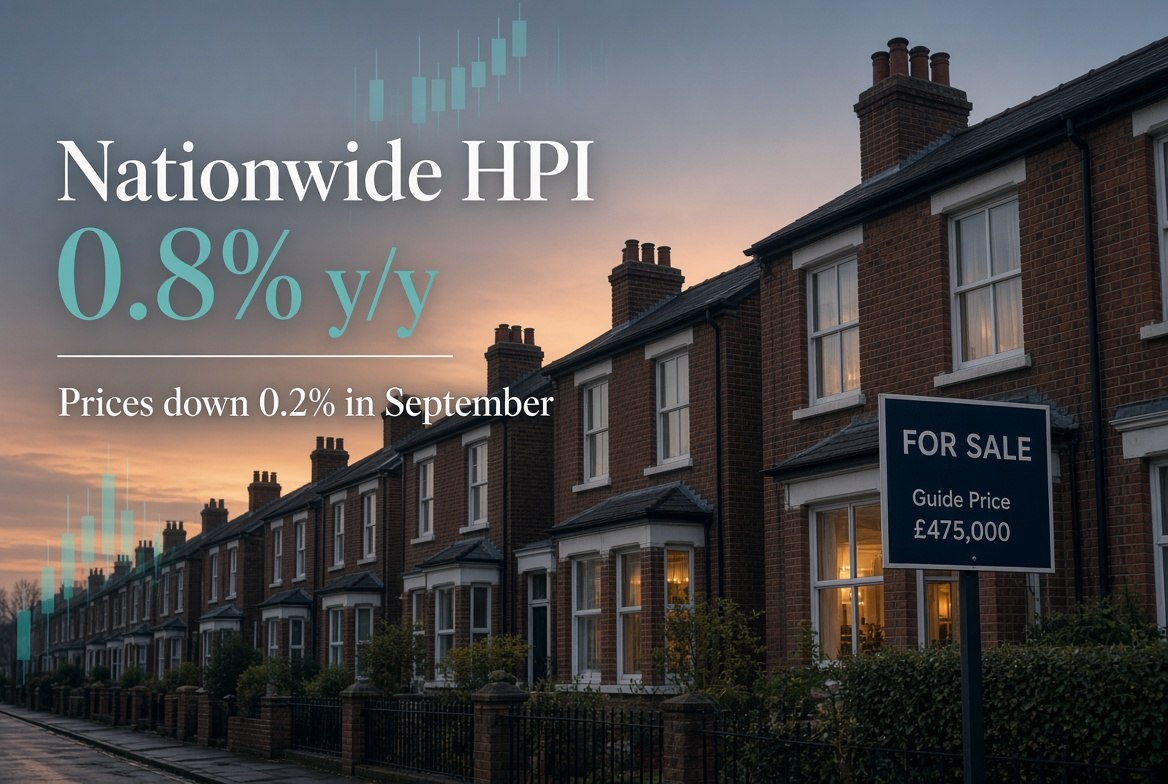
- Yesterday Q2 GDP was revised up to 0.5%. This morning Nationwide said prices fell 0.2% in September, with annual growth halved to 0.8%.
- Today: manufacturing PMI final at 09:30, eurozone unemployment at 10:00, US claims at 13:30, ISM at 15:00. Tomorrow: eurozone CPI at 10:00, US payrolls at 13:30.
- Expected mid-market ranges today: GBP/EUR €1.1600–€1.1701 | GBP/USD $1.3150–$1.3223.
- For a property payment, the rate is only one part of the equation. The cut-off around payrolls is the other.
Market Overview
The 24 September note went out with yields already fidgety and the Treasury floating a smaller fiscal buffer. The week since has been politics first. Healey’s conference speech promised the rules and said almost nothing about tax. Burnham’s first leader’s speech proposed that from 2030 the state pension rise by inflation or 2.5%, without the earnings link. A union motion for a wealth tax carried. Motions are not measures. The live argument is the 28 October Budget, with headroom of £23.6bn talked down towards £14bn in some reports, and a mansion-tax threshold cut from £2mn to £1.5mn still doing the rounds.
Markets have followed the arithmetic, not the conference hall. Yesterday’s GDP revision was a small mercy. This morning’s house-price print is the domestic headline. Friday still belongs to American jobs.
GBP/EUR Analysis
GBP/EUR: €1.1600–€1.1701 | Level: ~1.1705 (0.8544)
- The past day has spanned roughly 1.1695–1.1714, a net gain of about a tenth of a percent. Since 24 September this has been the steadier sterling pair: the dollar has done the damage elsewhere.
- The GDP upgrade to 0.5% helped. The cooler house-price print did not unsettle it.
- Budget politics matter more here than a PMI. Property-tax talk is a sterling story with a euro buyer attached.
- Eurozone unemployment is due at 10:00, seen unchanged at 6.4%. Friday’s flash CPI, previewed in the mid-3s, is the cleaner European risk.
Educational note: GBP/EUR is a relative price. It moves when the gap between UK and eurozone rate expectations shifts, not when a conference motion passes. Anyone pricing a European completion off a rate from the 24th should recheck it. The fourth decimal has been quiet. Completion dates are less so.
|
|
|
PROPERTY BUYER SPOTLIGHT
|
|
Timing, Range & the Bigger Picture
|
| |
Nationwide: September prices down 0.2%, annual growth halved to 0.8% from 1.6%, average price £274,251. Northern Ireland led at 5.9% year on year in the third quarter. East Anglia was weakest, down 0.7%.
This table illustrates the best and worst rate over a given time frame — highlighting the volatile nature of the FX markets and why timing is crucial.
| Period |
High |
Low |
£250k at High |
£250k at Low |
Difference |
| 1 Week |
1.1714 |
1.1623 |
€292,850 |
€290,575 |
€2,275 |
| 1 Month |
1.1714 |
1.1616 |
€292,850 |
€290,400 |
€2,450 |
| 3 Months |
1.1776 |
1.1616 |
€294,400 |
€290,400 |
€4,000 |
The numbers show movement is real even when markets feel quiet. Most buyers focus on the rate itself, yet the rate is only one part of the equation. Guidance on when to transfer, how the process is managed, clarity of communication and reliability of the people handling the money often make the larger difference. A slightly better rate with poor support or delays can cost more than a well-timed transfer executed smoothly.
For early-stage property buyers — and businesses moving larger sums — the real question is rarely just “what is the rate today?” It is “who will help navigate the timing, paperwork and practicalities so the money arrives exactly when needed, without stress?”
Want to see a different amount or timeline? try our useful calculator...
|
|
GBP/USD Analysis
GBP/USD: $1.3150–$1.3223 | Current: ~1.3228
- The past day has spanned roughly 1.3223–1.3284, leaving cable little changed on Wednesday’s close near 1.323. Since 24 September it is about 2% lower. Yields did that, not the conference.
- The Fed range has been 3.75–4.00% since 16 September. Another step is still being priced as data-dependent.
- Claims at 13:30 and ISM at 15:00 are this afternoon. August’s ISM was 54.6; surveys cluster around 54 to 55.
- Friday’s payrolls are the larger item: August was 162,000, September is seen near 90,000, unemployment steady at 4.1%.
Educational note: GBP/USD is a dollar story with a British footnote, and the footnote is the Budget. Anyone sending dollars off a rate circled on the 24th should treat 13:30 tomorrow as a known pinch point. The rate may be there. The paperwork needs to be there first.
EUR/USD Analysis
EUR/USD: ~1.1290
- A fraction softer than Wednesday’s close near 1.133, in a rough band of 1.1289–1.1337.
- Sterling has edged up on the day against both; the euro has not kept pace. That is why GBP/EUR still holds a 1.17 handle while cable does not.
- Factory PMI finals rarely reset the dollar trend. Unemployment at 10:00 is seen at 6.4%.
- Friday’s flash CPI, previewed near 3.6% after 3.2%, is the euro-specific risk. Payrolls will likely speak louder.
Educational note: EUR/USD still sets the tide for the European crosses. Into Friday the reading is two events, not one: European inflation first, American jobs second. A quiet Thursday is not a settled rate.
Weekly Economic Calendar
| Date |
Time (UK) |
Currency |
Event |
Actual / Forecast |
Previous |
Imp. |
| Wed 30 Sep |
07:00 |
GBP |
UK GDP QoQ (Q2, final) |
0.5% / 0.4% |
0.6% |
★★★ |
| Thu 1 Oct (Today) |
07:00 |
GBP |
Nationwide HPI MoM (Sep) |
−0.2% / 0.0% |
0.2% |
★★ |
| Thu 1 Oct (Today) |
07:00 |
GBP |
Nationwide HPI YoY (Sep) |
0.8% |
1.6% |
★★ |
| Thu 1 Oct (Today) |
09:30 |
GBP |
UK Manufacturing PMI (Sep, final) |
– / 52.0 |
51.7 |
★★ |
| Thu 1 Oct (Today) |
10:00 |
EUR |
Eurozone Unemployment Rate (Aug) |
– / 6.4% |
6.4% |
★★ |
| Thu 1 Oct (Today) |
13:30 |
USD |
US Initial Jobless Claims |
– / 205k |
197k |
★★ |
| Thu 1 Oct (Today) |
15:00 |
USD |
US ISM Manufacturing (Sep) |
– / 55.0 |
54.6 |
★★★ |
| Fri 2 Oct |
10:00 |
EUR |
Eurozone CPI Flash YoY (Sep) |
– / 3.6% |
3.2% |
★★★ |
| Fri 2 Oct |
13:30 |
USD |
US Nonfarm Payrolls (Sep) |
– / 90k |
162k |
★★★ |
| Fri 2 Oct |
13:30 |
USD |
US Unemployment Rate (Sep) |
– / 4.1% |
4.1% |
★★★ |
Conclusion
A week of conference speeches, a City verdict the pound ignored, and sterling has minded its own business against the euro while giving a little ground to the dollar. House prices have cooled without collapsing. Friday’s payrolls have not been told the country was otherwise engaged. None of this is a view on the rate, or on a football case. For property buyers and businesses, clean execution still does as much work as the fourth decimal place. Appeals can take years. Completions cannot.
This report is for informational purposes only and does not constitute financial advice.
For tailored currency handling solutions, whether for personal transfers or business needs, contact Excel Currencies for a free quote.
|
|

 X
 Facebook
 linkedin